Student Loan Interest Deduction 2026
Current year
For 2026, the Student Loan Interest Deduction figures are $2,500 (Maximum deduction), $85,000 (Phase-out threshold, single filers), $175,000 (Phase-out threshold, joint filers) and 2 more figures below.
| Item | Single filers | Joint filers |
|---|---|---|
| Phase-out threshold | $85,000 | $175,000 |
| Fully phased out | $100,000 | $205,000 |
Effective 2026-01-01Source: Rev. Proc. 2025-32 (IRS)Verified 2026-09-02
Compared with 2025
| Item | 2025 | 2026 | Change |
|---|---|---|---|
| Maximum deduction | $2,500 | $2,500 | +$0 (+0.0%) |
| Phase-out threshold, single filers | $85,000 | $85,000 | +$0 (+0.0%) |
| Phase-out threshold, joint filers | $170,000 | $175,000 | +$5,000 (+2.9%) |
| Fully phased out, single filers | $100,000 | $100,000 | +$0 (+0.0%) |
| Fully phased out, joint filers | $200,000 | $205,000 | +$5,000 (+2.5%) |
Phase-out threshold
Fully phased out
$85,000$205,000
One dot per column of the table, on a scale running from the smallest of these amounts to the largest. The scale is logarithmic - each faint line is ten times the one before it, so that the amounts crowded at the low end stay far enough apart to read. The table states which dot is which.
Who it applies to
The deduction reaches a taxpayer who paid interest on a qualified education loan under § 221 during a taxable year beginning in 2026, and how much of the $2,500 survives depends on modified adjusted gross income. Rev. Proc. 2025-32 states one pair of income figures for returns generally and a second, higher pair in parentheses for joint returns; a taxpayer whose modified adjusted gross income reaches the upper figure for their return type is completely phased out and deducts nothing. The revenue procedure states the amounts only. What counts as a qualified education loan, who may claim the interest, and how the phase-out is computed between the two income points are left to § 221 itself.
What changed this year, and why
The ceiling did not move. For taxable years beginning in 2026, Rev. Proc. 2025-32 states the maximum deduction for interest paid on qualified education loans under § 221 as $2,500, the same $2,500 Rev. Proc. 2024-40 stated for 2025. What moved is the income test: the procedure sets, as adjusted for inflation, the modified adjusted gross income above which the deduction begins to phase out under § 221(b) and the higher modified adjusted gross income at which it is completely phased out, and the pair of figures it gives for joint returns is higher than the pair Rev. Proc. 2024-40 gave for 2025. Rev. Proc. 2025-32 states its 2026 items for Code provisions as in effect on October 9, 2025.
Common questions
- What is the maximum student loan interest deduction for 2026?
- $2,500. Rev. Proc. 2025-32 describes it as the maximum deduction for interest paid on qualified education loans under § 221 for taxable years beginning in 2026. That figure is the ceiling before any income phase-out is applied, so a taxpayer above the relevant modified adjusted gross income limits deducts less than $2,500, or nothing at all.
- Did the student loan interest deduction change for 2026?
- The maximum did not. Rev. Proc. 2025-32 states $2,500 for taxable years beginning in 2026, the same amount Rev. Proc. 2024-40 stated for 2025. The income limits did move: the modified adjusted gross income figures for joint returns at which the deduction begins to phase out and at which it is completely phased out are both higher in Rev. Proc. 2025-32 than in the earlier procedure.
- At what income does the student loan interest deduction phase out in 2026?
- Rev. Proc. 2025-32 gives two income points. The $2,500 maximum begins to phase out under § 221(b) for taxpayers with modified adjusted gross income above a stated figure, and it is completely phased out for taxpayers whose modified adjusted gross income reaches a second, higher figure. Both points are stated as adjusted for inflation for taxable years beginning in 2026, and both are higher for a joint return.
- Can married couples filing jointly deduct more than $2,500?
- No. Rev. Proc. 2025-32 states one maximum deduction for interest paid on qualified education loans, $2,500, and states no doubled figure for a joint return. What changes on a joint return is the income test: the procedure gives higher modified adjusted gross income figures, in parentheses, for both the start and the end of the phase-out. The ceiling on the deduction itself is unchanged by filing status.
- Are there separate phase-out figures for head of household or single filers?
- Rev. Proc. 2025-32 states one pair of modified adjusted gross income figures that applies generally, with a second pair in parentheses for joint returns. It does not break the income limits out by any other filing status, so a single filer and a head of household read the same general figures. It also states no separate ceiling for either; the $2,500 maximum is common to all of them.
- Can my employer pay my student loan tax free in 2026?
- Rev. Proc. 2025-32 records that the One, Big, Beautiful Bill Act amended § 127(c) to make permanent the treatment of employer payments of principal or interest on a qualified education loan as educational assistance. The procedure states a maximum exclusion amount for that benefit and notes it will be adjusted for inflation for taxable years beginning after 2026. That exclusion is separate from the § 221 deduction and has its own ceiling.
- Which tax year does the $2,500 deduction apply to?
- Rev. Proc. 2025-32 states the interest on education loans item for taxable years beginning in 2026, and its effective date section applies the 2026 adjusted items to taxable years beginning in 2026. This item is not among those routed to the calendar year rule instead, so the figures follow the taxpayer's taxable year rather than the calendar year in which the interest happened to be paid.
- Where does the $2,500 student loan interest deduction come from?
- It is the maximum deduction under § 221 of the Internal Revenue Code. Rev. Proc. 2025-32 restates it, and publishes the inflation-adjusted phase-out limits that go with it, in its interest on education loans item. The procedure says the inflation-adjusted items it sets out are generally determined by reference to § 1(f), so the income limits track the statutory indexing rule rather than an annual discretionary choice.
Every amount on this page is a published figure rather than yours. The Student loan interest deduction for a single filer takes the number you enter and works it out against them, showing which published figure it used.
How the deduction is reduced inside the phase-out range
Inside the phase-out range the deduction is cut by a fraction rather than lost all at once. You begin with the interest you actually paid, capped at $2,500, and multiply it by a fraction. The numerator is the amount by which your modified adjusted gross income rises above the threshold for your filing status, which for 2026 is $85,000 for single filers and $175,000 on a joint return. The denominator is the width of the range between that threshold and the income at which the deduction disappears, which is $100,000 for single filers and $205,000 on a joint return. The product of that multiplication is the reduction, and you subtract it from the deduction you would otherwise have claimed. A taxpayer just above the threshold therefore keeps most of the deduction, while one near the top of the range keeps almost none of it. Publication 970 states the arithmetic in these words; the two ends of the range are the amounts this page publishes for 2026.
Phaseout. If your MAGI is within the range of incomes where the credit must be reduced, you must figure your re- duced deduction. To figure the phaseout, multiply your in- terest deduction (before the phaseout but not more than $2,500) by a fraction.
Publication 970 (2025), Tax Benefits for Education (IRS)
The income the phase-out is measured on
The income used to decide whether the student loan interest deduction is reduced is modified adjusted gross income (MAGI). For most taxpayers MAGI is simply the adjusted gross income shown on the federal income tax return, figured before subtracting any deduction for student loan interest, so the deduction itself is added back for this test. Other modifications can apply in particular situations, such as a return filed on Form 1040-NR or income excluded by a bona fide resident of Puerto Rico or American Samoa. The number that matters is therefore not the AGI on the face of the return in every case, and it is worth figuring before assuming the deduction is safe. For 2026 the reduction begins once MAGI passes $85,000 for single filers or $175,000 on a joint return, and the deduction is gone entirely at $100,000 and $205,000 respectively.
MAGI is AGI as figured on their federal income tax return before subtracting any deduction for student loan interest.
Publication 970 (2025), Tax Benefits for Education (IRS)
Who can claim the deduction
A taxpayer may claim the student loan interest deduction only if four conditions are all satisfied. First, the taxpayer's filing status must be any status except married filing separately. This means single filers, heads of household, qualifying surviving spouses, and married couples filing jointly are eligible, but married individuals filing separately are not. Second, no other taxpayer may claim the taxpayer as a dependent on their return. If another person lists the taxpayer as a dependent, neither the taxpayer nor that other person may deduct the student loan interest. Third, the taxpayer must be legally obligated to pay interest on a qualified student loan. Fourth, the taxpayer must have actually paid interest on that qualified student loan during the tax year. All four requirements must be met; failing any one of them disqualifies the deduction entirely. The maximum deduction is $2,500, subject to phase-out based on modified adjusted gross income.
Can You Claim the Deduction? Generally, you can claim the deduction if all of the follow- ing requirements are met. • Your filing status is any filing status except married fil- ing separately. • No one else is claiming you as a dependent on their tax return. • You are legally obligated to pay interest on a qualified student loan. • You paid interest on a qualified student loan.
Publication 970 (2025), Tax Benefits for Education (IRS)
Payments that do not count as student loan interest
Not every payment made toward a student loan counts as deductible interest. Three categories of payments are specifically excluded. First, interest paid on a loan does not qualify if the borrower is not legally obligated under the loan terms to make interest payments. Second, loan origination fees that are charges for property or services provided by the lender, such as commitment fees or processing costs, do not count as interest. Only origination fees that are charged for the use of money can be treated as deductible interest. Third, interest paid on a loan to the extent payments were made through participation in the National Health Service Corps Loan Repayment Program or certain other loan repayment assistance programs described in chapter 5 is excluded. A taxpayer who benefits from one of these programs cannot also claim a deduction for the same interest. These exclusions apply regardless of filing status or income level.
Don’t Include as Interest You can’t claim a student loan interest deduction for any of the following items. • Interest you paid on a loan if, under the terms of the loan, you aren’t legally obligated to make interest pay- ments. • Loan origination fees that are payments for property or services provided by the lender, such as commitment fees or processing costs. • Interest you paid on a loan to the extent payments were made through your participation in the National Health Service Corps Loan Repayment Program (the NHSC Loan Repayment Program) or certain other loan repayment assistance programs.
Publication 970 (2025), Tax Benefits for Education (IRS)
You can keep deducting interest for as long as the loan lasts
For the 2026 tax year, the IRS allows taxpayers to deduct up to $2,500 in interest paid on qualified student loans. This deduction remains available for as long as the borrower continues to make interest payments on the loan, with no time limit on how many years the deduction can be claimed. The IRS states that you can deduct all interest paid during the year on a student loan, including voluntary payments, until the loan is paid off. This means borrowers can continue to claim the deduction each year they pay interest, whether they are in a standard repayment plan, an income-driven repayment plan, or making extra payments to reduce the principal faster. The deduction phases out for single filers with modified adjusted gross income between $85,000 and $100,000, and for joint filers with income between $175,000 and $205,000. Once income exceeds these thresholds, the deduction is no longer available. However, as long as income remains below the phase-out range and the loan still has an outstanding balance on which interest is being paid, the deduction can be claimed annually.
When Must Interest Be Paid? You can deduct all interest you paid during the year on your student loan, including voluntary payments, until the loan is paid off.
Publication 970 (2025), Tax Benefits for Education (IRS)
Where the deduction actually lands on your return
For the 2026 tax year, the student loan interest deduction is claimed as an adjustment to income on the federal return. You enter the allowable amount on Schedule 1 (Form 1040), line 21. This means the deduction reduces your adjusted gross income directly, rather than being an itemized deduction on Schedule A. You do not need to itemize to claim this benefit. The maximum deduction allowed is $2,500 in interest per year. The deduction phases out for single filers with modified adjusted gross income between $85,000 and $100,000, and for joint filers between $175,000 and $205,000. Once income exceeds these thresholds, no deduction is available. However, as long as you remain below the phase-out range and meet all other eligibility requirements, you can claim the full $2,500 deduction each year by entering it on the appropriate line of Schedule 1.
Claiming the Deduction The student loan interest deduction is an adjustment to in- come. To claim the deduction, enter the allowable amount on Schedule 1 (Form 1040), line 21.
Publication 970 (2025), Tax Benefits for Education (IRS)
The same interest cannot be deducted twice under two different provisions
For the 2026 tax year, the IRS allows you to deduct up to $2,500 in interest paid on a qualified student loan. However, you cannot claim this deduction for any interest that is already deductible under a different provision of the tax code. The IRS states that you can't deduct as interest on a student loan any amount that is an allowable deduction under any other provision of the tax law, such as home mortgage interest. This rule prevents taxpayers from claiming the same interest expense twice under two different deductions. For example, if a loan qualifies as both a student loan and a home equity loan, and the interest is deductible as home mortgage interest, you cannot also deduct it as student loan interest. The deduction phases out for single filers with modified adjusted gross income between $85,000 and $100,000, and for joint filers between $175,000 and $205,000. You must ensure that any interest you claim as a student loan interest deduction is not being claimed elsewhere on your return.
No Double Benefit Allowed You can’t deduct as interest on a student loan any amount that is an allowable deduction under any other provision of the tax law (for example, home mortgage interest).
Publication 970 (2025), Tax Benefits for Education (IRS)
Refinancing for more than the original balance can disqualify all the interest
For the 2026 tax year, the IRS allows you to deduct up to $2,500 in interest paid on a qualified student loan. However, refinancing can jeopardize this deduction entirely. If you refinance a qualified student loan for more than your original loan balance and you use the additional amount for any purpose other than qualified education expenses, you can't deduct any interest paid on the refinanced loan. This means a cash-out refinance that includes non-educational expenses - such as paying off credit card debt, funding a vacation, or making home improvements - disqualifies the entire loan from the student loan interest deduction, not just the portion of interest attributable to the extra amount borrowed. The deduction phases out for single filers with modified adjusted gross income between $85,000 and $100,000, and for joint filers between $175,000 and $205,000. To preserve the deduction, a refinanced loan should be for the same amount as the original student loan, or any additional borrowing must be used solely for qualified education expenses as defined by the IRS.
If you refinance a qualified student loan for more than your original loan and you use the additional amount for any purpose other than qualified edu- cation expenses, you can’t deduct any interest paid on the refinanced loan.
Publication 970 (2025), Tax Benefits for Education (IRS)
How each figure was verified
Each number below was read from a stored copy of the document named beside it, and checked to occur word for word in the quoted sentence. The digest is of that stored text.
Rev. Proc. 2025-32 (IRS)
- Maximum deduction
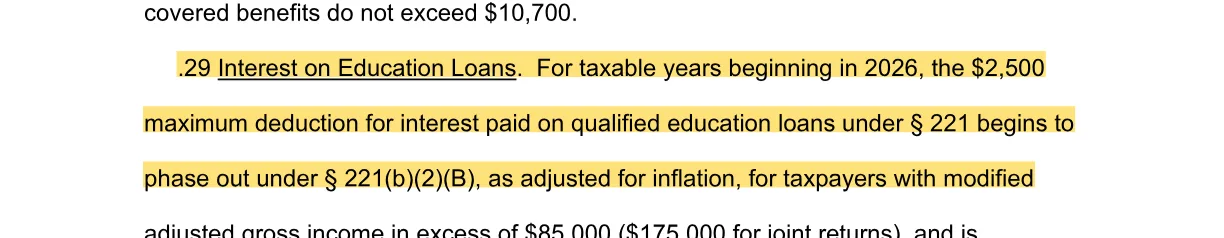
For taxable years beginning in 2026, the $2,500 maximum deduction for interest paid on qualified education loans under § 221 begins to phase out
- Phase-out threshold, single filers
begins to phase out under § 221(b)(2)(B), as adjusted for inflation, for taxpayers with modified adjusted gross income in excess of $85,000
- Phase-out threshold, joint filers
for taxpayers with modified adjusted gross income in excess of $85,000 ($175,000 for joint returns)
- Fully phased out, single filers
is completely phased out for taxpayers with modified adjusted gross income of $100,000 or more
- Fully phased out, joint filers
phased out for taxpayers with modified adjusted gross income of $100,000 or more ($205,000 or more for joint returns)
By year
Every published year
11 years on record, 2026 back to 2016. Each year links to its own page, its own document and its own verification date.
Oldest year at the left. Every line spans the same run of years, with a tick under each year it has a figure for, so a line that starts late is a column the law added late. The vertical axis is scaled to the values plotted rather than to zero, so a line shows the shape of the change and not the size of the amount. The table states every value.
| Year | Maximum deduction | Phase-out threshold, single filers | Phase-out threshold, joint filers | Fully phased out, single filers | Fully phased out, joint filers |
|---|---|---|---|---|---|
| 2026 | $2,500 | $85,000 | $175,000 | $100,000 | $205,000 |
| 2025 | $2,500 | $85,000 | $170,000 | $100,000 | $200,000 |
| 2024 | $2,500 | $80,000 | $165,000 | $95,000 | $195,000 |
| 2023 | $2,500 | $75,000 | $155,000 | $90,000 | $185,000 |
| 2022 | $2,500 | $70,000 | $145,000 | $85,000 | $175,000 |
| 2021 | $2,500 | $70,000 | $140,000 | $85,000 | $170,000 |
| 2020 | $2,500 | $70,000 | $140,000 | $85,000 | $170,000 |
| 2019 | $2,500 | $70,000 | $140,000 | $85,000 | $170,000 |
| 2018 | $2,500 | $65,000 | $135,000 | $80,000 | $165,000 |
| 2017 | $2,500 | $65,000 | $135,000 | $80,000 | $165,000 |
| 2016 | $2,500 | $65,000 | $130,000 | $80,000 | $160,000 |
Download every year as a csv. One row per published figure, each carrying the document it was read from and the date it was checked.
The same calculator for another year
- 2025 Student loan interest deduction on a joint return
- 2025 Student loan interest deduction for a single filer
- 2024 Student loan interest deduction on a joint return
- 2024 Student loan interest deduction for a single filer