Energy Efficient Home Improvement Credit 2026
Current year
The Energy Efficient Home Improvement Credit is not available for 2026: it ended after 2025-12-31.
Not available for 2026. This provision ended after 2025-12-31, so there is no 2026 figure to publish.
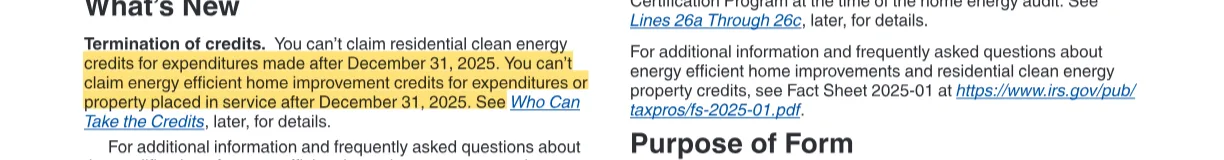
You can’t claim energy efficient home improvement credits for expenditures or property placed in service after December 31, 2025.
Ended after 2025-12-31Source: 2025 Instructions for Form 5695 (IRS)Verified 2026-09-04
Compared with 2025
| Item | 2025 | 2026 | Change |
|---|---|---|---|
| Annual credit limit | $1,200 | -1 | - |
| Heat pump and biomass annual credit limit | $2,000 | -1 | - |
- the One, Big, Beautiful Bill Act terminated § 25C for expenditures or property placed in service after December 31, 2025
Who it applies to
Taxpayers claiming the Energy Efficient Home Improvement Credit on Form 5695
What changed this year, and why
The Energy Efficient Home Improvement Credit terminated after December 31, 2025. No credit is available for expenditures or property placed in service after that date.
Common questions
- Is the Energy Efficient Home Improvement Credit available for 2026?
- No. The Energy Efficient Home Improvement Credit terminated after December 31, 2025. You cannot claim it for expenditures made or property placed in service after that date.
- Can I carry forward an unused credit from 2025 to 2026?
- No. The Energy Efficient Home Improvement Credit does not allow unused amounts to carry forward to a later year. Any credit you could not use against your 2025 tax liability is forfeited, not carried into 2026 or any later year. This is unlike the residential clean energy credit, which does allow a carryforward of unused amounts.
The credit ends with 2025
The IRS confirms that the energy efficient home improvement credit ends with 2025. Taxpayers cannot claim the credit for any expenditures, or for any property placed in service, after December 31, 2025. This termination applies specifically to the energy efficient home improvement credit reported on Form 5695; a separate termination rule applies to residential clean energy credits for expenditures made after the same date. The effect is that 2025 was the final year in which qualifying improvements - such as exterior doors, windows, insulation, heat pumps, biomass stoves, and home energy audits - could generate a federal credit under this provision. Costs paid or incurred in 2026 and later are ineligible, regardless of when the underlying contract was signed or the improvement was ordered. Anyone who wanted to rely on this credit needed the expenditure made, or the property placed in service, on or before December 31, 2025; that window has now closed.
You can’t claim energy efficient home improvement credits for expenditures or property placed in service after December 31, 2025.
2025 Instructions for Form 5695 (IRS)
The annual limit is a ceiling over smaller ceilings
The federal Energy Efficient Home Improvement Credit has a total combined annual limit, but within that total, individual categories have their own smaller ceilings. For qualifying exterior doors, the credit limit is $250 for any single door, and the total for all exterior doors combined cannot exceed $500. These per-item sublimits apply regardless of how much the taxpayer actually spends on the improvements. The structure means that even if a homeowner installs multiple exterior doors or spends more than the per-item caps, the credit is restricted to these specific dollar amounts. Taxpayers must track spending by category to determine the maximum credit available, as exceeding a sublimit does not allow the excess to be applied to other categories or to increase the overall credit beyond its total annual cap.
A credit limit of $250 for any qualifying exterior door and $500 total for all qualifying exterior doors.
2025 Instructions for Form 5695 (IRS)
Heat pumps get their own bucket
Before the credit ended, heat pumps, heat pump water heaters, biomass stoves and biomass boilers had their own separate annual credit limit, apart from the general limit that covered other qualified energy property. That separate limit carried no lifetime cap of its own.
Heat pumps and heat pump water heaters, biomass stoves and biomass boilers have a separate annual credit limit
2025 Instructions for Form 5695 (IRS)
The manufacturer number you must have
Beginning January 1, 2025, taxpayers claiming the federal Energy Efficient Home Improvement Credit for specified property placed into service in 2025 must include the qualified manufacturer identification number (QMID) for each item. The QMID is a four-character alphanumeric code that uniquely identifies the manufacturer of the qualified property. This requirement ensures that the property meets the energy efficiency standards necessary for the credit. Taxpayers should obtain the QMID from the manufacturer or retailer at the time of purchase and include it on Form 5695 when filing their federal tax return. Without the proper QMID, the credit may be disallowed, so it is essential to verify that the product documentation includes this identification number before claiming the credit.
Beginning January 1, 2025, if you are claiming the energy efficient home improvement credit for specified property placed into service in 2025, you must include the four-character alphanumeric unique qualified manufacturer identification number (QMID) for each item.
2025 Instructions for Form 5695 (IRS)
What makes an audit claimable
For an audit to qualify toward the 2026 Energy Efficient Home Improvement Credit, it must be performed by a Qualified Home Energy Auditor - or under that auditor's supervision - who holds current certification from a Qualified Certification Program at the time the audit is conducted. The written report the auditor provides must list the auditor's name and identifying number, include an attestation that the auditor is certified, and name the certification program. If any of these conditions is not met, for example if the auditor's certification has lapsed or the report omits the required information, the cost of the audit cannot be claimed as part of the credit. The IRS maintains details of these requirements in the instructions for the relevant lines of the form, and taxpayers should verify the auditor's credentials and the completeness of the report before paying, because an incomplete or uncertified audit simply does not count toward the credit.
The Qualified Home Energy Auditor must be certified by a Qualified Certification Program at the time of the home energy audit. See Lines 26a Through 26c, later, for details.
2025 Instructions for Form 5695 (IRS)
Subsidised money does not count
Under the federal Energy Efficient Home Improvement Credit, any amounts provided by subsidized energy financing cannot be used to calculate the credit. Subsidized energy financing refers to funding received under a federal, state, or local program where a principal purpose is to provide subsidized financing for projects designed to conserve energy or produce energy. This means that if a taxpayer receives low-interest loans, grants, rebates, or other financial assistance from government energy programs to pay for qualifying improvements, those subsidized amounts are excluded from the credit calculation. Only the taxpayer's own out-of-pocket expenses that are not covered by subsidized financing can be included when determining the credit amount. This rule prevents double benefits where taxpayers would receive both subsidized funding and a tax credit for the same expenditures.
Subsidized energy financing. Any amounts provided for by subsidized energy financing can't be used to figure the energy efficient home improvement credit. This is financing provided under a federal, state, or local program, a principal purpose of which is to provide subsidized financing for projects designed to conserve or produce energy.
2025 Instructions for Form 5695 (IRS)
New construction does not qualify, unlike its sibling credit
The 2026 Energy Efficient Home Improvement Credit applies exclusively to existing homes, unlike its sibling credit - the residential clean energy credit - which covers both existing homes and homes under construction. Expenses tied to building a new residence do not qualify. If a homeowner is making qualified improvements to an existing dwelling, including additions or renovations, those costs can be claimed. However, if the improvements are connected to constructing a new home, the taxpayer must indicate that fact on the form and cannot claim the credit for those expenses. The rule ensures the credit targets upgrades to the existing housing stock rather than new development.
The residential clean energy credit (Part I) is available for both existing homes and homes being constructed. The energy efficient home improvement credit (Part II) is only available for existing homes.
2025 Instructions for Form 5695 (IRS)
Unused credit is not carried forward, unlike the residential clean energy credit
Unlike the residential clean energy credit, any unused portion of the 2026 Energy Efficient Home Improvement Credit cannot be carried forward to future tax years. The residential clean energy credit allows taxpayers to carry excess credit amounts to 2026 if their tax liability prevents full use in the current year. The energy efficient home improvement credit does not offer this flexibility. If the credit exceeds the taxpayer's liability limitation for the year, the excess is forfeited rather than rolled over. Taxpayers should plan their energy efficiency improvements accordingly, knowing that any credit they cannot use in the current year will not be available later.
Also use Form 5695 to take any residential clean energy credit carryforward from 2024 or to carry the unused portion of the residential clean energy credit to 2026.
2025 Instructions for Form 5695 (IRS)
Without a valid manufacturer number for an item, that item gets no credit
To claim the 2026 Energy Efficient Home Improvement Credit for specified property, taxpayers must provide a valid QMID for each item. If an item lacks a valid QMID, no credit is allowed for that specific item, even if it otherwise qualifies. The QMID requirement ensures that products meet the necessary efficiency standards and can be properly verified. This rule applies to building envelope components, residential energy property, and other specified items covered under the credit. Taxpayers should verify that all products they purchase include valid QMIDs before installation to avoid losing the credit for non-compliant items.
Caution: To qualify for the energy efficient home improvement credit for specified property, you must provide a valid QMID for each item.
2025 Instructions for Form 5695 (IRS)
How this was verified
The statement below was read from a stored copy of the document named beside it, and checked to occur word for word in it. The digest is of that stored text.
2025 Instructions for Form 5695 (IRS)
- Ended after 2025-12-31
You can’t claim energy efficient home improvement credits for expenditures or property placed in service after December 31, 2025.
By year
The same calculator for another year
- 2025 Energy efficient home improvement credit headroom
- 2025 Heat pump credit headroom
- 2024 Energy efficient home improvement credit headroom
- 2024 Heat pump credit headroom
- 2023 Heat pump credit headroom