Defined Benefit Plan Limit 2026
Current year
For 2026, the Defined Benefit Plan Limit figures are $290,000 (Annual benefit under a defined benefit plan) and $72,000 (Defined contribution plan limit).
Effective 2026-01-01Source: Notice 2025-67 (IRS)Verified 2026-09-03
Compared with 2025
| Item | 2025 | 2026 | Change |
|---|---|---|---|
| Annual benefit under a defined benefit plan | $280,000 | $290,000 | +$10,000 (+3.6%) |
| Defined contribution plan limit | $70,000 | $72,000 | +$2,000 (+2.9%) |
Who it applies to
Sponsors and participants of qualified defined benefit and defined contribution retirement plans under Internal Revenue Code Section 415.
What changed this year, and why
For 2026, the IRS increased the annual benefit limit under a defined benefit plan to $290,000 and the defined contribution plan limit to $72,000.
Common questions
- What is the maximum annual benefit a defined benefit plan can pay in 2026?
- Effective January 1, 2026, the limitation on the annual benefit under a defined benefit plan under Section 415(b)(1)(A) is $290,000.
- What is the defined contribution plan limit for 2026?
- The limitation on contributions under a defined contribution plan under Section 415(c)(1)(A) is $72,000 for 2026.
Every amount on this page is a published figure rather than yours. The Plan limit headroom takes the number you enter and works it out against them, showing which published figure it used.
The benefit limit is the lesser of a dollar cap and your average pay
The IRS limits the annual retirement benefit a participant can receive under a defined benefit plan to the lesser of two amounts: 100% of the participant's average compensation for their highest 3 consecutive calendar years, or a specified dollar cap. For 2026, that dollar cap is $290,000. Because the limit is the lesser of the two figures, a participant whose average pay over their best three-year stretch falls below $290,000 will have their benefit limited to 100% of that lower average instead. The compensation figure is based on the three consecutive calendar years in which the participant earned the most, not necessarily the years immediately before retirement.
participant under a defined benefit plan can't exceed the lesser of the following amounts. 1. 100% of the participant's average compensation for their highest 3 consecutive calendar years.
Publication 560 (2025), Retirement Plans for Small Business (IRS)
What makes a plan a defined benefit plan
A defined benefit plan is defined as any plan that is not a defined contribution plan. Instead of specifying a fixed annual contribution amount, a defined benefit plan promises participants a specific benefit when they retire. The employer's annual contribution is calculated based on what is needed to fund those promised benefits. Because this calculation requires actuarial assumptions and computations - projecting future obligations and determining present values - ongoing professional assistance is generally required. For 2026, the annual benefit that can be paid to any participant under a defined benefit plan cannot exceed $290,000.
A defined benefit plan is any plan that isn't a defined con- tribution plan. Contributions to a defined benefit plan are based on what is needed to provide definitely determina- ble benefits to plan participants.
Publication 560 (2025), Retirement Plans for Small Business (IRS)
The compensation an employer may take into account
When calculating contributions and deductions for retirement plans, employers cannot use an employee's total pay without restriction. The law caps the amount of compensation that may be considered for each participant. For 2026, the maximum compensation that can be taken into account is $360,000 per employee. If an employee earns more than this amount, only $360,000 of their pay is used in plan calculations such as determining contribution limits or benefit accruals. This cap is adjusted periodically for inflation. The limitation applies across all qualified retirement plans, whether defined benefit or defined contribution, ensuring that highly compensated employees do not receive disproportionately large tax-advantaged retirement benefits based on income above this threshold.
The maximum compensation that can be taken into account for each employee in 2025 is $350,000 ($360,000 in 2026).
Publication 560 (2025), Retirement Plans for Small Business (IRS)
The separate limit on a defined contribution plan
The IRS places a separate ceiling on defined contribution plans. For 2026, the annual contributions and other additions (excluding earnings) allocated to a participant's account cannot exceed the lesser of 100% of the participant's compensation or $72,000. This limit applies to the total of employer contributions, employee contributions, and forfeitures allocated to the account for the year. Because earnings are excluded from the calculation, investment growth inside the account does not count against the cap. The defined contribution limit operates independently from the defined benefit limit, so each type of plan has its own ceiling. Catch-up contributions made by participants age 50 or older are not subject to this limit and may be added on top of the regular amount.
a defined contri- bution plan's annual contributions and other additions (ex- cluding earnings) to the account of a participant can't ex- ceed the lesser of the following amounts. 1. 100% of the participant's compensation.
Publication 560 (2025), Retirement Plans for Small Business (IRS)
Why the deduction has to be figured by an actuary
Unlike defined contribution plans where the contribution amount is straightforward, defined benefit plans require complex calculations to determine how much the employer must contribute each year. These calculations involve actuarial assumptions about factors such as employee mortality, retirement ages, salary projections, and investment returns. The deduction for contributions to a defined benefit plan is based on actuarial assumptions and computations. Consequently, an actuary must figure your deduction limit. The IRS requires this professional analysis because the contribution amount depends on projecting future benefit obligations and determining the present value of those obligations. Attempting to calculate this deduction without actuarial expertise could result in incorrect figures that do not comply with tax law requirements.
The deduction for contributions to a defined benefit plan is based on actuarial assump- tions and computations. Consequently, an actuary must figure your deduction limit.
Publication 560 (2025), Retirement Plans for Small Business (IRS)
How many employees the plan has to cover
A defined benefit plan cannot qualify unless it covers a minimum number of workers. Specifically, it must benefit at least the lesser of 50 employees or the greater of (a) 40% of all employees or (b) 2 employees. If the employer has only one employee, the plan must cover that person. This floor exists so the plan serves a broad group of the workforce, not just the owner or a handful of highly compensated staff, and it operates alongside the nondiscrimination rules that also forbid favoring highly compensated employees. The coverage test is applied at the plan level and is separate from the annual benefit limit, which for 2026 caps the benefit payable to any one participant at $290,000. Even a plan that pays benefits well below that cap still has to clear the minimum-coverage test to maintain its qualified status and the tax advantages that go with it.
Minimum coverage requirement must be met. To be a qualified plan, a defined benefit plan must benefit at least the lesser of the following. 1. 50 employees. 2. The greater of: a. 40% of all employees, or b. Two employees. If there is only one employee, the plan must benefit that employee.
Publication 560 (2025), Retirement Plans for Small Business (IRS)
The plan has to exist before the year it covers ends
An employer that wants a tax deduction for a defined benefit plan contribution for a given tax year must have the plan formally in place - that is, adopted - by the last day of that year. Adopting the plan after December 31 of the year the contributions are for means the contribution is not deductible for that year, even if the money is deposited before the tax return is filed. The rule applies to all qualified plans, including defined benefit plans covering self-employed individuals and their employees. For a sole proprietor who is the only participant in a new section 401(k) plan adopted after the end of the tax year, elective deferrals must instead be paid into the plan before the return's due date (without extensions) to be treated as made by the end of the first plan year. Because the deduction is tied to the adoption date, employers typically finalize plan documents well before year-end rather than relying on filing deadlines. The contribution itself remains subject to the 2026 annual benefit limit of $290,000 per participant regardless of when the plan is adopted.
Set-up deadline. To take a deduction for contributions for a tax year, your plan must be set up (adopted) by the last day of that year.
Publication 560 (2025), Retirement Plans for Small Business (IRS)
Contributions above the deduction limit are not lost, just delayed
If an employer contributes more to a qualified plan than the deduction limit allows for the year, the excess is not forfeited. Instead, the difference may be carried over and deducted in a later year, combined with the contribution made for that later year. The total deduction claimed in the later year is still capped at 25% of the participating employees' compensation for that year (with a separate reduction for contributions made on behalf of self-employed individuals). For purposes of applying this 25% cap, a SEP is treated as a profit-sharing defined contribution plan. The amount carried over and deducted may itself be subject to the excise tax on nondeductible contributions discussed elsewhere in the same chapter, so the excess is preserved but not free from cost while it waits to be used. The carryover rule applies regardless of whether the plan is a defined benefit plan or a defined contribution plan, and it operates alongside the 2026 defined benefit annual benefit limit of $290,000 per participant and the 2026 defined contribution limit of $72,000, which cap what can be paid out or credited to a participant in a single year.
Carryover of Excess Contributions If you contribute more to a plan than you can deduct for the year, you can carry over and deduct the difference in later years, combined with your contributions for those years. Your combined deduction in a later year is limited to 25% of the participating employees' compensation for that year.
Publication 560 (2025), Retirement Plans for Small Business (IRS)
Contributing more than the limit can trigger a 10% excise tax, but not for a defined benefit plan's minimum funding
Contributing more than the allowable deduction limit to a qualified retirement plan produces nondeductible contributions, and those generally attract a 10% excise tax. The tax applies to nondeductible contributions made to qualified pension plans, profit-sharing plans, and SEPs, and is reported on Form 5330. However, there is an important special rule for self-employed individuals: the 10% excise tax does not apply to any contribution made to satisfy the minimum funding requirements of a money purchase pension plan or a defined benefit plan. Even if that required minimum-funding contribution exceeds the individual's earned income from the trade or business for which the plan was established, the excess is not subject to the excise tax. The protection is narrow - it covers only the amount needed to meet the minimum funding standard, not any additional discretionary overfunding. For 2026, the defined benefit plan annual benefit limit is $290,000 per participant and the defined contribution plan limit is $72,000, but the excise tax question turns on the deduction limit, not those benefit and contribution caps.
Excise Tax for Nondeductible (Excess) Contributions If you contribute more than your deduction limit to a retire- ment plan, you have made nondeductible contributions and you may be liable for an excise tax. In general, a 10% excise tax applies to nondeductible contributions made to qualified pension and profit-sharing plans and to SEPs. Special rule for self-employed individuals. The 10% excise tax doesn't apply to any contribution made to meet the minimum funding requirements in a money purchase pension plan or a defined benefit plan. Even if that contri- bution is more than your earned income from the trade or business for which the plan is set up, the difference isn't subject to this excise tax.
Publication 560 (2025), Retirement Plans for Small Business (IRS)
How each figure was verified
Each number below was read from a stored copy of the document named beside it, and checked to occur word for word in the quoted sentence. The digest is of that stored text.
Notice 2025-67 (IRS)
- Annual benefit under a defined benefit plan
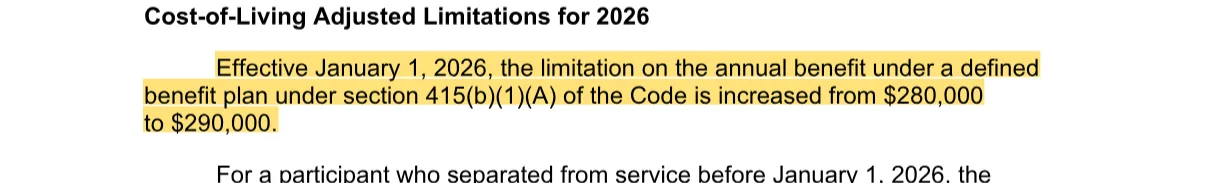
Effective January 1, 2026, the limitation on the annual benefit under a defined benefit plan under section 415(b)(1)(A) of the Code is increased from $280,000 to $290,000.
- Defined contribution plan limit
The limitation for defined contribution plans under section 415(c)(1)(A) is increased in 2026 from $70,000 to $72,000.
By year
Every published year
11 years on record, 2026 back to 2016. Each year links to its own page, its own document and its own verification date.
Oldest year at the left. Every line spans the same run of years, with a tick under each year it has a figure for, so a line that starts late is a column the law added late. The vertical axis is scaled to the values plotted rather than to zero, so a line shows the shape of the change and not the size of the amount. The table states every value.
Download every year as a csv. One row per published figure, each carrying the document it was read from and the date it was checked.