SALT Deduction Limit 2026
Current year
For 2026, the SALT Deduction Limit figures are $40,400 (Deduction limit), $20,200 (Deduction limit, married filing separately), $505,000 (Phase-down threshold (MAGI)) and 4 more figures below.
| Item | Amount | Married filing separately |
|---|---|---|
| Deduction limit | $40,400 | $20,200 |
| Phase-down threshold (MAGI) | $505,000 | $252,500 |
| Phase-down floor | $10,000 | $5,000 |
Effective 2026-01-01Source: Publication 505 (2026), Tax Withholding and Estimated Tax (IRS)Verified 2026-09-04
Phase-down rateSource: 2025 Instructions for Schedule A (Form 1040) (IRS)Verified 2026-09-04
Compared with 2025
| Item | 2025 | 2026 | Change |
|---|---|---|---|
| Deduction limit | $40,000 | $40,400 | +$400 (+1.0%) |
| Deduction limit, married filing separately | $20,000 | $20,200 | +$200 (+1.0%) |
| Phase-down threshold (MAGI) | $500,000 | $505,000 | +$5,000 (+1.0%) |
| Phase-down threshold (MAGI), married filing separately | $250,000 | $252,500 | +$2,500 (+1.0%) |
| Phase-down floor | $10,000 | $10,000 | +$0 (+0.0%) |
| Phase-down floor, married filing separately | $5,000 | $5,000 | +$0 (+0.0%) |
| Phase-down rate | 30% | 30% | +0% (+0.0%) |
Who it applies to
Taxpayers who itemize deductions on Schedule A (Form 1040) and claim state and local income, sales, or property taxes.
What changed this year, and why
For 2026, the overall limit on the deduction for state and local income, sales, and property taxes increased to $40,400. The limit for married individuals filing separately is half the full amount, $20,200. The limit is subject to reduction based on modified adjusted gross income but will not be reduced below a statutory floor. See the Instructions for Schedule A (Form 1040) for more information.
Common questions
- What is the SALT deduction limit?
- The SALT deduction limit is the maximum amount a taxpayer may deduct on Schedule A for state and local income, sales, and property taxes combined. For 2026, that cap is $40,400.
- What is the SALT deduction limit for married filing separately in 2026?
- $20,200 for 2026, half of the $40,400 limit that applies to other filing statuses. The income-based reduction is halved too: for a separate return it starts once modified adjusted gross income exceeds $252,500, and the limit will not be reduced below $5,000.
- Does income affect the SALT deduction limit?
- Yes. The limit is reduced if modified adjusted gross income exceeds certain thresholds, though it will not be reduced below a floor. See the Instructions for Schedule A (Form 1040) for details.
- How does the 2026 limit compare to prior years?
- The limit was $40,000 for 2025. For 2026, it increased modestly.
Every amount on this page is a published figure rather than yours. The SALT deduction after the income phase-down takes the number you enter and works it out against them, showing which published figure it used.
The limit shrinks above a stated income
For 2026, the overall SALT deduction limit of $40,400 shrinks for higher earners. Taxpayers whose modified adjusted gross income (MAGI) exceeds $505,000 ($252,500 if married filing separately) see that limit gradually phased down. The phase-down has a floor: the IRS states the limit will not be reduced below $10,000 ($5,000 if married filing separately). That means no matter how far above the MAGI threshold a taxpayer's income rises, the deduction for state and local income, sales, and property taxes can never fall beneath that minimum. Taxpayers with MAGI at or below the threshold face no reduction at all.
the overall limit is reduced if your modified adjusted gross in- come is more than $505,000 ($252,500 if mar- ried filing separately) but will not be reduced be- low $10,000 ($5,000 if married filing separately).
Publication 505 (2026), Tax Withholding and Estimated Tax (IRS)
Income taxes or sales taxes, one or the other
Taxpayers have the option to deduct either state and local income taxes or state and local general sales taxes on their federal return, but cannot claim both categories in the same tax year. This election applies to the total amount of state and local taxes subject to the overall SALT cap. Most taxpayers choose to deduct income taxes because the amount withheld from wages typically exceeds their sales tax burden. However, residents of states with no income tax may benefit from electing the sales tax deduction instead. The choice is made on Line 5a of Schedule A, and once you elect one category, you forgo any deduction for the other. Both options count toward the same overall limitation on state and local tax deductions, so the election affects which taxes qualify but does not increase the total amount you can deduct beyond the statutory cap.
Line 5a You can elect to deduct state and local general sales taxes instead of state and local income taxes. You can't deduct both.
2025 Instructions for Schedule A (Form 1040) (IRS)
What is not a deductible tax
The IRS identifies several classes of taxes that are never deductible as itemized deductions on Schedule A. Federal income tax and most federal excise taxes are excluded. Payroll-type taxes - Social Security, Medicare, federal unemployment (FUTA), and railroad retirement (RRTA) taxes - cannot be deducted. Customs duties and federal estate and gift taxes are likewise non-deductible (though a separate credit may apply for estate tax paid on income in respect of a decedent). At the state and local level, taxes on gasoline, car inspection fees, assessments for sidewalks or other property improvements, tax paid on behalf of someone else, and license fees such as marriage, driver's, or pet licenses are excluded. Foreign personal or real property taxes also do not count toward the SALT deduction.
Taxes You Paid Taxes You Can't Deduct • Federal income and most excise taxes. • Social security, Medicare, federal unemployment (FUTA), and railroad retirement (RRTA) taxes. • Customs duties. • Federal estate and gift taxes. However, see Line 16, later, if you had income in respect of a decedent.TIP • Certain state and local taxes, including tax on gasoline, car inspection fees, assessments for sidewalks or other improvements to your property, tax you paid for someone else, and license fees (for example, marriage, driver's, and pet). • Foreign personal or real property taxes.
2025 Instructions for Schedule A (Form 1040) (IRS)
Payroll contributions that do count
Mandatory employee contributions to certain state disability and unemployment insurance programs qualify as deductible state and local taxes. These include required payroll deductions for state disability benefit funds in California, New Jersey, and New York, as well as the Rhode Island Temporary Disability Benefit Fund and Washington State Supplemental Workmen's Compensation Fund. Mandatory contributions to state unemployment funds in Alaska, California, New Jersey, and Pennsylvania also count. Additionally, required payments to state family leave programs, such as New Jersey Family Leave Insurance and California Paid Family Leave, are deductible. These contributions differ from voluntary insurance premiums because they are compulsory payroll withholdings mandated by state law. They appear on your wage statements and represent actual tax payments to state governments, which is why they qualify for inclusion in the SALT deduction calculation alongside other state and local income taxes.
Mandatory contributions you made to the California, New Jersey, or New York Nonoccupational Disability Benefit Fund; Rhode Island Temporary Disability Benefit Fund; or Washington State Supplemental Workmen's Compensation Fund. • Mandatory contributions to the Alaska, California, New Jersey, or Pennsylvania state unemployment fund. • Mandatory contributions to state family leave programs, such as the New Jersey Family Leave Insurance (FLI) program and the California Paid Family Leave program.
2025 Instructions for Schedule A (Form 1040) (IRS)
You only get this if you itemize
The SALT deduction is only available to taxpayers who itemize their deductions on Schedule A rather than claiming the standard deduction. When you file your federal return, you compare your total itemized deductions to your standard deduction and choose the larger amount. If your itemized deductions exceed the standard deduction, you benefit from itemizing and can claim the SALT deduction along with other qualifying expenses like mortgage interest and charitable contributions. However, if your standard deduction is larger, you take that amount instead and receive no separate benefit from state and local taxes paid. This choice is particularly relevant for taxpayers whose total itemizable expenses fall below the standard deduction threshold, as they cannot claim any portion of the SALT deduction regardless of how much they paid in state and local taxes during the year.
In most cases, your federal income tax will be less if you take the larger of your itemized deductions or your standard deduction.
2025 Instructions for Schedule A (Form 1040) (IRS)
Prepaying next year's property tax before it is assessed doesn't count this year
For the 2026 tax year, prepaying property taxes that won't be assessed until 2027 doesn't allow you to claim them on your 2026 return. The IRS requires that property taxes must be both paid during the tax year and assessed before the following year begins. This means if you try to pay your 2027 property tax bill in late 2026 before your local government has officially assessed it, those payments won't count toward your 2026 SALT deduction. State or local law determines when a property tax is considered assessed, which typically happens when you become legally liable for the tax. This rule prevents taxpayers from accelerating deductions into an earlier year simply by making early payments on taxes that haven't yet been formally imposed by the taxing authority.
You must look at your real estate tax bill to decide if any nondeductible itemized charges, such as those listed earlier, are included in the bill. If your taxing authority (or lender) doesn't furnish you a copy of your real estate tax bill, ask for it. Prepayment of next year's property taxes. Only taxes paid in 2025 and assessed prior to 2026 can be deducted for 2025. State or local law determines whether and when a property tax is assessed, which is generally when the taxpayer becomes liable for the property tax imposed.
2025 Instructions for Schedule A (Form 1040) (IRS)
A refund of tax you already deducted can come back as income
If you receive a refund of state or local taxes that you previously deducted and that deduction actually reduced your tax liability in the earlier year, you may need to report the refund as income in the year you receive it. This is because the tax benefit rule prevents you from getting a double benefit: once from the deduction in the earlier year and again from keeping the refunded amount tax-free. The refund goes on Schedule 1 (Form 1040), line 8z. However, if you received a refund of taxes you paid in the same year, you simply reduce your current deduction rather than reporting income. The key distinction is whether the deduction in the prior year actually lowered your tax bill. Publication 525 provides detailed guidance on how to calculate the taxable portion of recoveries.
if you deducted your actual state and local general sales taxes in the earlier year and the deduction reduced your tax, you may have to include the refund in income on Schedule 1 (Form 1040), line 8z.
2025 Instructions for Schedule A (Form 1040) (IRS)
How each figure was verified
Each number below was read from a stored copy of the document named beside it, and checked to occur word for word in the quoted sentence. The digest is of that stored text.
Publication 505 (2026), Tax Withholding and Estimated Tax (IRS)
- Deduction limit
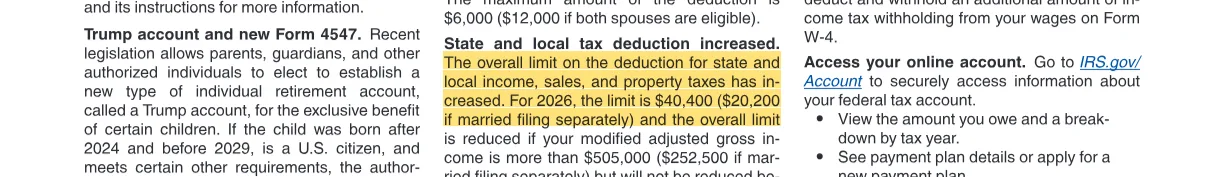
The overall limit on the deduction for state and local income, sales, and property taxes has in- creased. For 2026, the limit is $40,400 ($20,200 if married filing separately)
- Deduction limit, married filing separately
The overall limit on the deduction for state and local income, sales, and property taxes has in- creased. For 2026, the limit is $40,400 ($20,200 if married filing separately)
- Phase-down threshold (MAGI)
modified adjusted gross in- come is more than $505,000 ($252,500 if mar- ried filing separately) but will not be reduced be- low $10,000 ($5,000 if married filing separately).
- Phase-down threshold (MAGI), married filing separately
modified adjusted gross in- come is more than $505,000 ($252,500 if mar- ried filing separately) but will not be reduced be- low $10,000 ($5,000 if married filing separately).
- Phase-down floor
modified adjusted gross in- come is more than $505,000 ($252,500 if mar- ried filing separately) but will not be reduced be- low $10,000 ($5,000 if married filing separately).
- Phase-down floor, married filing separately
modified adjusted gross in- come is more than $505,000 ($252,500 if mar- ried filing separately) but will not be reduced be- low $10,000 ($5,000 if married filing separately).
2025 Instructions for Schedule A (Form 1040) (IRS)
- Phase-down rate
Multiply line 6 by 30% (0.30)
By year
Every published year
9 years on record, 2026 back to 2018. Each year links to its own page, its own document and its own verification date.
Oldest year at the left. Every line spans the same run of years, with a tick under each year it has a figure for, so a line that starts late is a column the law added late. The vertical axis is scaled to the values plotted rather than to zero, so a line shows the shape of the change and not the size of the amount. The table states every value.
| Year | Deduction limit | Deduction limit, married filing separately | Phase-down threshold (MAGI) | Phase-down threshold (MAGI), married filing separately | Phase-down floor | Phase-down floor, married filing separately | Phase-down rate |
|---|---|---|---|---|---|---|---|
| 2026 | $40,400 | $20,200 | $505,000 | $252,500 | $10,000 | $5,000 | 30% |
| 2025 | $40,000 | $20,000 | $500,000 | $250,000 | $10,000 | $5,000 | 30% |
| 2024 | $10,000 | $5,000 | -1 | -1 | -2 | -2 | -3 |
| 2023 | $10,000 | $5,000 | -1 | -1 | -2 | -2 | -3 |
| 2022 | $10,000 | $5,000 | -1 | -1 | -2 | -2 | -3 |
| 2021 | $10,000 | $5,000 | -1 | -1 | -2 | -2 | -3 |
| 2020 | $10,000 | $5,000 | -1 | -1 | -2 | -2 | -3 |
| 2019 | $10,000 | $5,000 | -1 | -1 | -2 | -2 | -3 |
| 2018 | $10,000 | $5,000 | -1 | -1 | -2 | -2 | -3 |
- the MAGI phase-down of the SALT deduction limit is an addition to section 164(b)(6) made by the One, Big, Beautiful Bill Act, effective for taxable years beginning after 2024. Before then the limit was a flat dollar cap with no income-based reduction
- the MAGI phase-down of the SALT deduction limit is an addition to section 164(b)(6) made by the One, Big, Beautiful Bill Act, effective for taxable years beginning after 2024. Before then the limit was a flat dollar cap with no floor to state, because it had no phase-down
- the MAGI phase-down of the SALT deduction limit is an addition to section 164(b)(6) made by the One, Big, Beautiful Bill Act, effective for taxable years beginning after 2024. Before then there was no phase-down rate to state
Download every year as a csv. One row per published figure, each carrying the document it was read from and the date it was checked.
The same calculator for another year
- 2025 SALT deduction after the income phase-down
- 2025 SALT deduction after phase-down, filing separately