Capital Gains Tax Rate 2026
Current year
For 2026, the Capital Gains Tax Rate figures are $98,900 (Top of the 0% bracket, joint filers), $613,700 (Top of the 15% bracket, joint filers), $49,450 (Top of the 0% bracket, married filing separately) and 9 more figures below.
| Item | Rate | Joint filers | Married filing separately | Heads of household | Single filers | Estates and trusts |
|---|---|---|---|---|---|---|
| Top of the 0% bracket | - | $98,900 | $49,450 | $66,200 | $49,450 | $3,300 |
| Top of the 15% bracket | 15% | $613,700 | $306,850 | $579,600 | $545,500 | $16,250 |
| Rate above the 15% bracket | 20% | - | - | - | - | - |
A dash is a figure this site has not published for that row, not an amount of zero.
Effective 2026-01-01Source: Rev. Proc. 2025-32 (IRS)Verified 2026-09-03
Rate above the 15% bracketSource: Topic no. 409, Capital gains and losses (IRS)Verified 2026-09-03
Compared with 2025
| Item | 2025 | 2026 | Change |
|---|---|---|---|
| Top of the 0% bracket, joint filers | $96,700 | $98,900 | +$2,200 (+2.3%) |
| Top of the 15% bracket, joint filers | $600,050 | $613,700 | +$13,650 (+2.3%) |
| Top of the 0% bracket, married filing separately | $48,350 | $49,450 | +$1,100 (+2.3%) |
| Top of the 15% bracket, married filing separately | $300,000 | $306,850 | +$6,850 (+2.3%) |
| Top of the 0% bracket, heads of household | $64,750 | $66,200 | +$1,450 (+2.2%) |
| Top of the 15% bracket, heads of household | $566,700 | $579,600 | +$12,900 (+2.3%) |
| Top of the 0% bracket, single filers | $48,350 | $49,450 | +$1,100 (+2.3%) |
| Top of the 15% bracket, single filers | $533,400 | $545,500 | +$12,100 (+2.3%) |
| Top of the 0% bracket, estates and trusts | $3,250 | $3,300 | +$50 (+1.5%) |
| Top of the 15% bracket, estates and trusts | $15,900 | $16,250 | +$350 (+2.2%) |
| Rate above the 0% bracket | 15% | 15% | +0% (+0.0%) |
| Rate above the 15% bracket | 20% | 20% | +0% (+0.0%) |
Top of the 0% bracket
Top of the 15% bracket
$3,300$613,700
One dot per column of the table, on a scale running from the smallest of these amounts to the largest. The scale is logarithmic - each faint line is ten times the one before it, so that the amounts crowded at the low end stay far enough apart to read. The table states which dot is which.
Who it applies to
Taxpayers with long-term capital gains, including individuals filing as joint, married filing separately, head of household, single, and estates and trusts.
What changed this year, and why
For 2026, the IRS adjusted the long-term capital gains rate thresholds for inflation. The bracket tops increased compared to 2025. For example, the lowest bracket top for joint filers increased from $96,700 to $98,900, and the 15% bracket top for joint filers increased from $600,050 to $613,700. The tax rates remain unchanged.
Common questions
- What are the long-term capital gains tax rates for 2026?
- For long-term capital gains in 2026, section 1(h) provides a rate structure with thresholds that depend on filing status. The first threshold — the maximum amount taxed at the lowest rate — is $98,900 for joint filers, $49,450 for married filing separately, $66,200 for heads of household, $49,450 for single filers, and $3,300 for estates and trusts. Gains above this first threshold and up to the second threshold are taxed at 15%. The second threshold is $613,700 for joint filers, $306,850 for married filing separately, $579,600 for heads of household, $545,500 for single filers, and $16,250 for estates and trusts. Gains above the second threshold are taxed at 20%.
Every amount on this page is a published figure rather than yours. The Room left in the 0% capital gains bracket takes the number you enter and works it out against them, showing which published figure it used.
What the lower rates actually apply to
For 2026, the reduced capital gains rates of 15%, 20%, 25%, and 28% apply only to net capital gain, not to all investment proceeds. The IRS defines net capital gain as the amount by which your net long-term capital gain for the year exceeds your net short-term capital loss. You must first net your long-term gains and losses separately from your short-term gains and losses. Only if the long-term side produces a positive result that is larger than any net short-term loss do you have a net capital gain eligible for the preferential rates. For most taxpayers, "other gain" from assets like stocks and mutual funds falls into the 15% or 20% brackets depending on taxable income, or the 0% bracket for those in the lowest ordinary rate brackets. For single filers in 2026, the top of the 0% bracket is $49,450 and the top of the 15% bracket is $545,500; above that threshold, the 20% rate applies. For joint filers, the 0% bracket tops out at $98,900 and the 15% bracket at $613,700. Gains from collectibles and certain qualified small business stock are taxed at 28%, and unrecaptured section 1250 gain is taxed at 25%. If the regular tax computation produces a lower tax than the maximum capital gain rate computation, the regular computation applies instead.
These lower rates are called the maximum capital gain rates. The term “net capital gain” means the amount by which your net long-term capital gain for the year is more than your net short-term capital loss. For 2025, the maximum capital gain rates are 0%, 15%, 20%, 25%, and 28%.
Publication 550 (2025), Investment Income and Expenses (IRS)
How long you must hold to get the long-term rate
For 2026, your holding period determines whether a capital gain or loss from investment property is short-term or long-term, which in turn determines whether the reduced maximum capital gain rates apply. You hold investment property more than 1 year if the period from the day after you acquired it through the day you disposed of it is longer than 1 year; in that case, any capital gain or loss is long-term and may qualify for the preferential rates. If you hold the property 1 year or less, the gain or loss is short-term and is taxed at ordinary income rates. Counting begins the day after the acquisition date, and the disposition date is included in the holding period. For securities traded on an established market, use the trade date rather than the settlement date for both the start and end of the period. Special rules apply to digital assets, which are treated as property and follow the same holding period principles.
If you hold investment prop- erty more than 1 year, any capital gain or loss is a long-term capital gain or loss. If you hold the property 1 year or less, any capital gain or loss is a short-term capital gain or loss.
Publication 550 (2025), Investment Income and Expenses (IRS)
How much of a loss you can deduct in one year
When your capital losses exceed your capital gains in a tax year, you can deduct the net loss against other income, but only up to a limit. The allowable capital loss deduction is the lesser of $3,000 ($1,500 if married filing separately) or your total net loss shown on line 16 of Schedule D (Form 1040). This means you can reduce your ordinary income dollar for dollar by up to $3,000 of net capital loss each year. If your total net loss is greater than $3,000, the excess is not lost - it carries over to the next tax year and is treated as if incurred in that year. You can continue carrying over unused losses to later years until they are completely used up. When you carry a loss forward, it keeps its original character: a long-term capital loss carried over reduces the next year's long-term capital gains before it reduces short-term capital gains. The carryover amount equals your total net loss minus the lesser of your allowable deduction for the year or your taxable income increased by that allowable deduction. Losses carried over from a joint return filed in a prior year can only be deducted on the return of the spouse who actually incurred the loss if you now file separately.
Limit on deduction. Your allowable capital loss deduc- tion, figured on Schedule D (Form 1040), is the lesser of: • $3,000 ($1,500 if you are married and file a separate return), or • Your total net loss as shown on line 16 of Schedule D (Form 1040).
Publication 550 (2025), Investment Income and Expenses (IRS)
The loss you cannot deduct if you buy back in
If you sell stock or securities at a loss and buy substantially identical stock or securities within 30 days before or after the sale, the loss is disallowed under the wash sale rules. The 30-day window runs both directions, so buying 30 days before the sale triggers the rule just as buying 30 days after does. The rule also applies if your spouse or a corporation you control buys the substantially identical stock, if you acquire the replacement through a fully taxable trade, if you acquire a contract or option to buy substantially identical stock, or if you acquire substantially identical stock inside an IRA or Roth IRA. The loss is not permanently forfeited. Instead, the disallowed loss is added to the cost basis of the replacement stock, and the holding period of the replacement includes the holding period of the stock sold. This postpones the deduction until the new stock is eventually disposed of. Wash sale rules apply to losses on contracts and options to acquire stock or securities, but not to losses on commodity futures contracts or foreign currencies.
A wash sale occurs when you sell or trade stock or se- curities at a loss and within 30 days before or after the sale you: 1. Buy substantially identical stock or securities, 2. Acquire substantially identical stock or securities in a fully taxable trade, 3. Acquire a contract or option to buy substantially iden- tical stock or securities, or 4. Acquire substantially identical stock for your individual retirement arrangement (IRA) or Roth IRA.
Publication 550 (2025), Investment Income and Expenses (IRS)
The extra tax on top of the capital gain rate
In addition to the regular capital gains tax, certain taxpayers owe the Net Investment Income Tax, also known as NIIT. The NIIT is a 3.8% tax on the lesser of your net investment income or the amount by which your modified adjusted gross income exceeds a threshold that depends on your filing status. For married taxpayers filing jointly or qualifying surviving spouses, the threshold is $250,000. For married taxpayers filing separately, the threshold is $125,000. For single filers and heads of household, the threshold is $200,000. Estates and trusts are also subject to the NIIT on undistributed net investment income to the extent it exceeds the dollar amount at which the highest tax bracket begins for an estate or trust. The NIIT is imposed under Code section 1411 and reported on Form 8960. Because capital gains are included in net investment income, the 3.8% NIIT is added on top of whatever capital gain rate applies, whether 15% or 20%. For example, a joint filer with modified adjusted gross income above $250,000 who has long-term capital gains taxed at 15% will also owe the additional 3.8% on the lesser of net investment income or the amount of modified adjusted gross income over $250,000.
Net investment income tax (NIIT). The NIIT is a 3.8% tax on the lesser of your net investment income or the amount of your modified adjusted gross income (MAGI) that is over a threshold amount based on your filing status. Filing Status Threshold Amount Married Filing Jointly or Qualifying Surviving Spouse $250,000 Married Filing Separately $125,000 Single or Head of Household $200,000
Publication 550 (2025), Investment Income and Expenses (IRS)
Certain hedges force you to recognize the gain before you actually sell
The IRS treats certain hedging transactions as constructive sales of appreciated financial positions. If you enter into a short sale of the same or substantially identical property, an offsetting notional principal contract, or similar transactions that eliminate most of your risk of loss and opportunity for gain, you must recognize gain as if you had sold the position at its fair market value on the date of the constructive sale. This resets your holding period, so when you eventually dispose of the position you reduce your gain (or increase your loss) by the amount already recognized. The rule prevents taxpayers from locking in gains while deferring the tax through offsetting positions.
You are treated as having made a constructive sale when you enter into certain transactions involving an appreci- ated financial position (defined later) in stock, a partner- ship interest, or certain debt instruments.
Publication 550 (2025), Investment Income and Expenses (IRS)
There is no flat-rate line - a worksheet blends the rates against your income
Long-term capital gains are not taxed at a single flat rate on a line of the return. Instead, the IRS requires taxpayers to use either the Qualified Dividends and Capital Gain Tax Worksheet or the Schedule D Tax Worksheet to figure the tax. The worksheet blends the 15% and 20% rates against taxable income, allocating gain across the brackets based on how much room remains in each rate threshold. The effective rate on the gain depends on the taxpayer's filing status and income level.
Tax computation using maximum capital gain rates. Use the Qualified Dividends and Capital Gain Tax Work- sheet or the Schedule D Tax Worksheet (whichever ap- plies) to figure your tax if you have qualified dividends or net capital gain.
Publication 550 (2025), Investment Income and Expenses (IRS)
How each figure was verified
Each number below was read from a stored copy of the document named beside it, and checked to occur word for word in the quoted sentence. The digest is of that stored text.
Rev. Proc. 2025-32 (IRS)
- Top of the 0% bracket, joint filers
Married Individuals Filing Joint Returns and Surviving Spouse $98,900
- Top of the 15% bracket, joint filers
Married Individuals Filing Joint Returns and Surviving Spouse $98,900 $613,700
- Top of the 0% bracket, married filing separately
Married Individuals Filing Separate Returns $49,450
- Top of the 15% bracket, married filing separately
Married Individuals Filing Separate Returns $49,450 $306,850
- Top of the 0% bracket, heads of household
Heads of Household $66,200
- Top of the 15% bracket, heads of household
Heads of Household $66,200 $579,600
- Top of the 0% bracket, single filers
All Other Individuals $49,450
- Top of the 15% bracket, single filers
All Other Individuals $49,450 $545,500
- Top of the 0% bracket, estates and trusts
Estates and Trusts $3,300
- Top of the 15% bracket, estates and trusts
Estates and Trusts $3,300 $16,250
- Rate above the 0% bracket
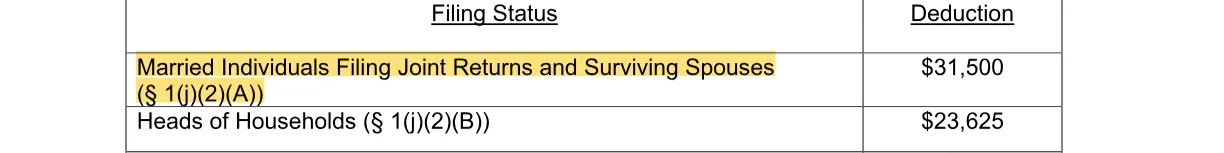
For taxable years beginning in 2026, the maximum zero rate amounts and maximum 15 percent rate amounts under § 1(j)(5)(B), as adjusted for inflation, are as follows:
Topic no. 409, Capital gains and losses (IRS)
- Rate above the 15% bracket
However, a capital gains rate of 20% applies to the extent that your taxable income exceeds the thresholds set for the 15% capital gain rate.
By year
Not published here
- 2018 — Source unavailable. We have not found a source that safely states these 2018 bracket thresholds.
Every published year
10 years on record, 2026 back to 2016. Each year links to its own page, its own document and its own verification date.
Oldest year at the left. Every line spans the same run of years, with a tick under each year it has a figure for, so a line that starts late is a column the law added late. The vertical axis is scaled to the values plotted rather than to zero, so a line shows the shape of the change and not the size of the amount. The table states every value.
| Year | Top of the 0% bracket, single filers | Top of the 0% bracket, joint filers | Top of the 0% bracket, married filing separately | Top of the 0% bracket, heads of household | Top of the 0% bracket, estates and trusts | Top of the 15% bracket, single filers | Top of the 15% bracket, joint filers | Top of the 15% bracket, married filing separately | Top of the 15% bracket, heads of household | Top of the 15% bracket, estates and trusts | Rate above the 0% bracket | Rate above the 15% bracket |
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 2026 | $49,450 | $98,900 | $49,450 | $66,200 | $3,300 | $545,500 | $613,700 | $306,850 | $579,600 | $16,250 | 15% | 20% |
| 2025 | $48,350 | $96,700 | $48,350 | $64,750 | $3,250 | $533,400 | $600,050 | $300,000 | $566,700 | $15,900 | 15% | 20% |
| 2024 | $47,025 | $94,050 | $47,025 | $63,000 | $3,150 | $518,900 | $583,750 | $291,850 | $551,350 | $15,450 | 15% | 20% |
| 2023 | $44,625 | $89,250 | $44,625 | $59,750 | $3,000 | $492,300 | $553,850 | $276,900 | $523,050 | $14,650 | 15% | 20% |
| 2022 | $41,675 | $83,350 | $41,675 | $55,800 | $2,800 | $459,750 | $517,200 | $258,600 | $488,500 | $13,700 | 15% | 20% |
| 2021 | $40,400 | $80,800 | $40,400 | $54,100 | $2,700 | $445,850 | $501,600 | $250,800 | $473,750 | $13,250 | 15% | 20% |
| 2020 | $40,000 | $80,000 | $40,000 | $53,600 | $2,650 | $441,450 | $496,600 | $248,300 | $469,050 | $13,150 | 15% | 20% |
| 2019 | $39,375 | $78,750 | $39,375 | $52,750 | $2,650 | $434,550 | $488,850 | $244,425 | $461,700 | $12,950 | 15% | 20% |
| 2017 | -1 | -1 | -1 | -1 | -1 | -1 | -1 | -1 | -1 | -1 | 15% | 20% |
| 2016 | -1 | -1 | -1 | -1 | -1 | -1 | -1 | -1 | -1 | -1 | 15% | 20% |
- before the Tax Cuts and Jobs Act, § 1(h) set the capital gains rate by reference to which ordinary income tax bracket the taxpayer fell in, not by a capital-gains-specific breakpoint of its own. The Act added § 1(j)(5), which set standalone, inflation-indexed breakpoints starting in 2018
Download every year as a csv. One row per published figure, each carrying the document it was read from and the date it was checked.
The same calculator for another year
- 2025 Room left in the 15% capital gains bracket
- 2025 Room left in the 0% capital gains bracket
- 2024 Room left in the 15% capital gains bracket
- 2024 Room left in the 0% capital gains bracket