Kiddie Tax Threshold 2026
Current year
For 2026, the Kiddie Tax Threshold figures are $1,350 (Unearned income reduction amount) and $2,700 (Unearned income filing trigger).
Effective 2026-01-01Source: Rev. Proc. 2025-32 (IRS)Verified 2026-09-03
Unearned income filing triggerSource: 2025 Instructions for Form 8615, Tax for Certain Children Who Have Unearned Income (IRS)Verified 2026-09-03
Compared with 2025
Every figure on this page is unchanged from 2025.
| Item | 2025 | 2026 | Change |
|---|---|---|---|
| Unearned income reduction amount | $1,350 | $1,350 | +$0 (+0.0%) |
| Unearned income filing trigger | $2,700 | $2,700 | +$0 (+0.0%) |
Who it applies to
The amount is applied on the return of a child whose unearned income falls under the § 1(g) kiddie tax for a taxable year beginning in 2026. It works as a reduction against net unearned income rather than as an exemption from the rule, so the child remains inside the kiddie tax regime and the figure only sets how much unearned income escapes it. The same figure also matters to a parent, because the revenue procedure uses it to frame the gross income range in which a parent may elect to report the child's income on the parent's own return. Rev. Proc. 2025-32 sets the amount and does not restate which children § 1(g) reaches.
What changed this year, and why
The kiddie tax amount did not move. For taxable years beginning in 2026, Rev. Proc. 2025-32 sets at $1,350 the amount in § 1(g) used to reduce the net unearned income reported on a child's return that is subject to the kiddie tax, the same $1,350 that Rev. Proc. 2024-40 stated for taxable years beginning in 2025. The revenue procedure again notes that this figure is the same as the amount provided in § 63 for a dependent's standard deduction, as adjusted for inflation, and that the same $1,350 is used under § 1(g) to determine whether a parent may elect to include a child's gross income in the parent's gross income. The One, Big, Beautiful Bill Act changes that Rev. Proc. 2025-32 exists to reflect do not include § 1(g).
Common questions
- What is the kiddie tax unearned income amount for 2026?
- For taxable years beginning in 2026 the amount in § 1(g) used to reduce the net unearned income reported on the child's return that is subject to the kiddie tax is $1,350. Rev. Proc. 2025-32 states it as an inflation-adjusted item. It is a reduction applied to unearned income, not a cut-off that removes a child from § 1(g) altogether.
- Did the kiddie tax threshold change for 2026?
- No. Rev. Proc. 2025-32 states $1,350 for taxable years beginning in 2026, the same figure Rev. Proc. 2024-40 stated for taxable years beginning in 2025. The amount is an inflation-adjusted item determined by reference to § 1(f), and an indexed figure can be republished unchanged from one year to the next. The legislation Rev. Proc. 2025-32 was issued to reflect did not amend § 1(g) either.
- What does the $1,350 kiddie tax amount actually do?
- It reduces the net unearned income reported on the child's return that is subject to the kiddie tax. Rev. Proc. 2025-32 describes the figure that way rather than as an exemption or a filing trigger. The reduction is applied to unearned income specifically; the revenue procedure states no equivalent figure for the child's earned income under § 1(g).
- Can a parent report a child's income on their own return in 2026?
- Rev. Proc. 2025-32 states that the same $1,350 is used for purposes of § 1(g) to determine whether a parent may elect to include a child's gross income in the parent's gross income and to calculate the kiddie tax. The figure therefore does double duty: it sizes the reduction on the child's own return and it sets the bottom of the income band in which the parental election can be considered.
- What income range lets a parent make the kiddie tax election for 2026?
- The revenue procedure gives one requirement as an example: the child's gross income must be more than the amount referred to in § 1(g), which is $1,350 for 2026, but less than a multiple of that amount which § 1(g) itself specifies. Rev. Proc. 2025-32 sets out only that requirement; the remaining conditions on the election live in the Code section rather than in the revenue procedure.
- Is the kiddie tax amount the same as the dependent standard deduction?
- Rev. Proc. 2025-32 says the $1,350 kiddie tax amount is the same as the amount provided in § 63, as adjusted for inflation. In the standard deduction item, the deduction for an individual who may be claimed as a dependent by another taxpayer cannot exceed the greater of that same figure or the sum of the individual's earned income and a further amount the procedure states. The two provisions are indexed together.
- Does the kiddie tax affect the alternative minimum tax in 2026?
- Yes, and Rev. Proc. 2025-32 handles it as a separate item. For a child to whom the § 1(g) kiddie tax applies, the exemption amount under § 55 and § 59(j) for alternative minimum tax purposes may not exceed the sum of the child's earned income for the taxable year plus a fixed amount stated in that item. That AMT figure is a different number from the $1,350 unearned income reduction and moves on its own schedule.
- Which tax year does the $1,350 kiddie tax amount apply to?
- Rev. Proc. 2025-32 states it for taxable years beginning in 2026, and the effective date section applies the 2026 adjusted items to taxable years beginning in 2026. Unearned income of minor children is not one of the items routed to the procedure's calendar year rule instead. The figure therefore attaches to the child's taxable year, not to the date on which the unearned income was received.
Every amount on this page is a published figure rather than yours. The Kiddie tax threshold headroom takes the number you enter and works it out against them, showing which published figure it used.
The five conditions, and the three age tests
A child is subject to the Kiddie Tax and must file Form 8615 only if all five of the following conditions are met: (1) the child had more than $2,700 of unearned income; (2) the child is required to file a tax return; (3) the child satisfies one of three age tests; (4) at least one parent was alive at the end of the year; and (5) the child does not file a joint return. The three age tests in condition 3 are: (a) the child was under age 18 at the end of 2025; (b) the child was age 18 and did not have earned income exceeding half of his or her support; or (c) the child was a full-time student at least age 19 and under age 24 and did not have earned income exceeding half of his or her support. The term "child" includes a legally adopted child and a stepchild. These rules apply whether or not the child is a dependent, but they do not apply if neither parent was living at the end of the year.
Form 8615 must be filed for any child who meets all of the following conditions. 1. The child had more than $2,700 of unearned income. 2. The child is required to file a tax return. 3. The child either: a. Was under age 18 at the end of 2025, b. Was age 18 at the end of 2025 and didn’t have earned income that was more than half of the child's support, or c. Was a full-time student at least age 19 and under age 24 at the end of 2025 and didn’t have earned income that was more than half of the child's support. (Earned income is defined later. Support is defined below.) 4. At least one of the child's parents was alive at the end of 2025. 5. The child doesn’t file a joint return for 2025.
2025 Instructions for Form 8615, Tax for Certain Children Who Have Unearned Income (IRS)
What counts as unearned income
The IRS treats a child's unearned income as income that comes from investments or other sources rather than from working. The $1,350 reduction amount is subtracted from the child's unearned income to determine the portion subject to the parent's tax rate. For 2026, if a child's unearned income exceeds $2,700, that excess is taxed at the parent's marginal rate rather than the child's typically lower rate. This ensures that families cannot shift large amounts of investment income to children in lower tax brackets to avoid taxes. The parent's rate applies only when it is higher than the child's own rate. Children under age 18, and certain older children who meet specific criteria, must use Form 8615 to calculate the tax if their unearned income exceeds the $2,700 filing trigger.
Unearned income is generally all income other than salaries, wages, and other amounts received as pay for work actually performed (earned income).
2025 Instructions for Form 8615, Tax for Certain Children Who Have Unearned Income (IRS)
The support test that decides whether an older child is caught
For the kiddie tax to apply in 2026, an older child must meet a support test. If the child was age 18 at the end of the year, or was a full-time student at least age 19 and under age 24, the tax only applies if the child did not have earned income that was more than half of the child's support. This means that if an older teenager or young adult earns enough from working to pay for more than half of their own living expenses, they are generally not subject to the kiddie tax rules. Support includes amounts spent to provide the child with food, lodging, clothing, education, medical and dental care, recreation, transportation, and similar necessities. A scholarship received by a full-time student is not counted as support. If the child's earned income exceeds half of their total support, the special rules for taxing a child's unearned income at the parent's rate do not apply.
Was age 18 at the end of 2025 and didn’t have earned income that was more than half of the child's support
2025 Instructions for Form 8615, Tax for Certain Children Who Have Unearned Income (IRS)
Reporting the child's income on the parent's return instead
Under the Kiddie Tax rules, a child who meets all of the conditions for filing Form 8615 may avoid that filing if the parent makes an election. A parent may elect to report the child's interest, ordinary dividends, and capital gain distributions directly on the parent's own return. If the parent makes this election, the child does not have to file a tax return or Form 8615 at all. For complete details on the requirements and consequences of this election, the parent should consult Form 8814, Parents' Election To Report Child's Interest and Dividends.
The parent may be able to elect to report the child’s interest, ordinary dividends, and capital gain distributions on the parent’s return. If the parent makes this election, the child won’t have to file a return or Form 8615. However, the federal income tax on the child’s income, including qualified dividends and capital gain distributions, may be higher if this election is made. For more details, see Form 8814, Parents’ Election To Report Child's Interest and Dividends.
2025 Instructions for Form 8615, Tax for Certain Children Who Have Unearned Income (IRS)
Why the child's own bracket is not the end of it
For 2026, a child who is under 18 (or is an older student or otherwise meets the Who Must File tests) and has more than $2,700 of unearned income does not simply pay tax at the child’s own usually-low rate. Instead, the portion of unearned income above the $1,350 reduction is taxed at whichever is higher: the child’s own rate or the parent’s rate. In most cases the parent’s rate is higher, so the IRS requires the family to complete Form 8615 to figure the child’s tax using the parent’s taxable income and filing status as the starting point. The purpose is to prevent a family from shifting investment income to a child and paying a lower rate than the parent would have paid. The form is only filed when unearned income crosses the $2,700 filing trigger; below that amount the child’s regular tax brackets apply without reference to the parents.
For children under age 18 and certain older children described below in Who Must File, unearned income over $2,700 is taxed at the parent's rate if the parent's rate is higher than the child's. If the child's unearned income is more than $2,700, use Form 8615 to figure the child's tax.
2025 Instructions for Form 8615, Tax for Certain Children Who Have Unearned Income (IRS)
A January 1 birthday counts the child a year older
For purposes of the kiddie tax, a child's age is determined as of December 31 of the tax year. This means a child born on January 1 is considered a year older than their actual birth date would suggest at year-end. For example, a child born on January 1, 2008 is considered 18 at the end of 2025, even though they wouldn't turn 18 until January 1, 2026. This age quirk can affect whether the child meets the conditions for being subject to the kiddie tax. The IRS provides a chart to help determine if children with these specific January 1 birthdays meet the age requirements, as being just one day off could push a child into a different age category for tax purposes.
Certain January 1 birthdays. Use the following chart to determine whether certain children with January 1 birthdays meet condition 3 under Who Must File, earlier. IF you were born on... THEN, at the end of 2025, you are considered to be... January 1, 2008 18*
2025 Instructions for Form 8615, Tax for Certain Children Who Have Unearned Income (IRS)
A capital loss bigger than the offset does not just disappear
When figuring a child's unearned income for the kiddie tax, capital losses reduce capital gains dollar for dollar. If the child's capital losses exceed their capital gains, up to $3,000 of that excess can offset other unearned income such as interest and dividends. Any amount of capital loss that exceeds the $3,000 allowance does not simply vanish. The excess is carried forward to the following tax year, where it is treated as a capital loss again and can be used against future capital gains and other unearned income. This carryover means a child who has a large investment loss in one year may still have that loss working for them in subsequent years, reducing unearned income reported on the Form 8615 in those later years.
If the capital losses are more than the capital gains, the difference (up to $3,000 ($1,500 in the case of a married individual filing a separate return)) is subtracted from your child’s interest, dividends, and other unearned income. Any difference over $3,000 is carried to the next year.
2025 Instructions for Form 8615, Tax for Certain Children Who Have Unearned Income (IRS)
If a parent's income later changes, the child's tax has to be refigured
The kiddie tax calculation on Form 8615 uses the parents' tax information to determine the child's liability. If, after the child's return is filed, the parents' income changes, the entire kiddie tax computation must be redone with the corrected figures. The child's tax is also recalculated if the net unearned income of any other children subject to the kiddie tax changes, because each sibling's amount affects the others. When the recomputation produces a different tax liability, the child must file Form 1040-X, the Amended U.S. Individual Income Tax Return, to report the change. This requirement ensures that the child's tax stays aligned with the actual family income even after the original return has been submitted.
If the parents’ income changes after the child’s return is filed, the child’s tax must be refigured using the adjusted amounts. The child's tax must also be refigured if there are changes to the net unearned income of other children for whom the parent is required to file a Form 8615. If the child's tax changes, file Form 1040-X.
2025 Instructions for Form 8615, Tax for Certain Children Who Have Unearned Income (IRS)
How each figure was verified
Each number below was read from a stored copy of the document named beside it, and checked to occur word for word in the quoted sentence. The digest is of that stored text.
Rev. Proc. 2025-32 (IRS)
- Unearned income reduction amount
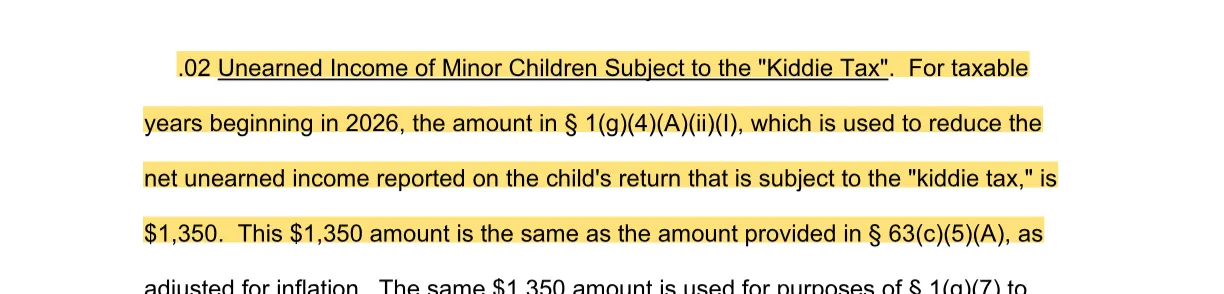
For taxable years beginning in 2026, the amount in § 1(g)(4)(A)(ii)(I), which is used to reduce the net unearned income reported on the child's return that is subject to the "kiddie tax," is $1,350.
2025 Instructions for Form 8615, Tax for Certain Children Who Have Unearned Income (IRS)
- Unearned income filing trigger
1. The child had more than $2,700 of unearned income.
By year
Every published year
11 years on record, 2026 back to 2016. Each year links to its own page, its own document and its own verification date.
Oldest year at the left. Every line spans the same run of years, with a tick under each year it has a figure for, so a line that starts late is a column the law added late. The vertical axis is scaled to the values plotted rather than to zero, so a line shows the shape of the change and not the size of the amount. The table states every value.
Download every year as a csv. One row per published figure, each carrying the document it was read from and the date it was checked.