Section 179 expensing after the phase-down, 2026
This works out one number from the Section 179 Deduction Limit figures published for 2026. Every amount it uses is below, with the document it was read from. What you enter is your own: this site has no way to check it, and the answer it produces is not a published figure.
This calculates
The Section 179 amount after the published dollar-for-dollar phase-down and property cost you enter.
You provide
- Cost of qualifying property placed in service this year
It does not include
- Whether property qualifies, business-income limits, depreciation, elections, or a complete return.
Effective 2026-01-01Source: Rev. Proc. 2025-32 (IRS)Verified 2026-09-03
How it is worked out
The published dollar limit, reduced one dollar for every dollar your total cost of qualifying property placed in service this year exceeds the published threshold, never below zero - then whichever is smaller, that reduced limit or what you entered as placed in service. Rounded to the nearest cent.
It uses Maximum section 179 expensing deduction, $2,560,000 and Phase-out threshold: cost of section 179 property placed in service, $4,090,000, published above.
Figures in this colour are computed from the amounts above. They are not published figures and no document states them.
Work it out
The live calculator needs JavaScript. The table below covers common amounts and is computed the same way.
Worked out for common amounts
| Cost of qualifying property placed in service this year | Result |
|---|---|
| 500,000 | $500,000 |
| 4,000,000 | $2,560,000 |
| 4,500,000 | $2,150,000 |
| 6,500,000 | $150,000 |
How each figure was verified
Each number below was read from a stored copy of the document named beside it, and checked to occur word for word in the quoted sentence. The digest is of that stored text.
Rev. Proc. 2025-32 (IRS)
- Maximum section 179 expensing deduction
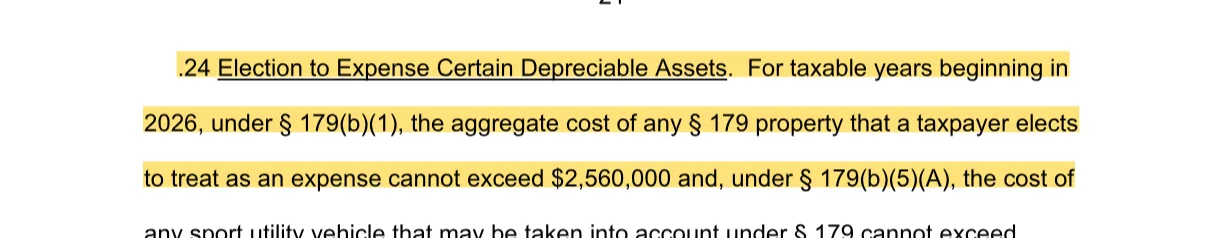
Election to Expense Certain Depreciable Assets. For taxable years beginning in 2026, under § 179(b)(1), the aggregate cost of any § 179 property that a taxpayer elects to treat as an expense cannot exceed $2,560,000
- Phase-out threshold: cost of section 179 property placed in service
Under § 179(b)(2), the $2,560,000 limitation under § 179(b)(1) is reduced (but not below zero) by the amount by which the cost of § 179 property placed in service during the 2026 taxable year exceeds $4,090,000.
Every 2026 Section 179 Deduction Limit figure · Section 179 Deduction Limit in every year · Every calculator on this site