2026 Roth IRA Income Limit
For 2026, the Roth IRA Income Limit figures are $153,000 (Phase-out start, single filers), $168,000 (Phase-out end, single filers), $242,000 (Phase-out start, joint filers) and 4 more figures below.
| Item | Single filers | Joint filers | Separate filers |
|---|---|---|---|
| Phase-out start | $153,000 | $242,000 | $0 |
| Phase-out end | $168,000 | $252,000 | $10,000 |
Effective 2026-01-01Source: Notice 2025-67 (IRS)Verified 2026-09-03
Compared with 2025
| Item | 2025 | 2026 | Change |
|---|---|---|---|
| Phase-out start, single filers | $150,000 | $153,000 | +$3,000 (+2.0%) |
| Phase-out end, single filers | $165,000 | $168,000 | +$3,000 (+1.8%) |
| Phase-out start, joint filers | $236,000 | $242,000 | +$6,000 (+2.5%) |
| Phase-out end, joint filers | $246,000 | $252,000 | +$6,000 (+2.4%) |
| Annual IRA contribution limit | $7,000 | $7,500 | +$500 (+7.1%) |
| Phase-out start, separate filers | $0 | $0 | +$0 |
| Phase-out end, separate filers | $10,000 | $10,000 | +$0 (+0.0%) |
Phase-out start
Phase-out end
$10,000$252,000
One dot per column of the table, on a scale running from the smallest of these amounts to the largest. The scale is logarithmic - each faint line is ten times the one before it, so that the amounts crowded at the low end stay far enough apart to read. The table states which dot is which.
Who it applies to
The range applies to a taxpayer contributing to a Roth IRA, and which range applies is decided by filing status and by adjusted gross income for the year. Married couples filing jointly, and taxpayers filing as a qualifying widow(er), use the range that starts at $242,000 and ends at $252,000. Singles and heads of household use the range that starts at $153,000 and ends at $168,000. A married individual filing a separate return is treated differently again: Notice 2025-67 states that this phase-out range is not subject to an annual cost-of-living adjustment, so it did not move for 2026 while the other two did. That range runs from $0 to $10,000 of adjusted gross income. A taxpayer whose adjusted gross income is below the start of the applicable range is not touched by the phase-out at all, and is instead limited only by the separate dollar ceiling on IRA contributions that the same notice sets under section 219.
What changed this year, and why
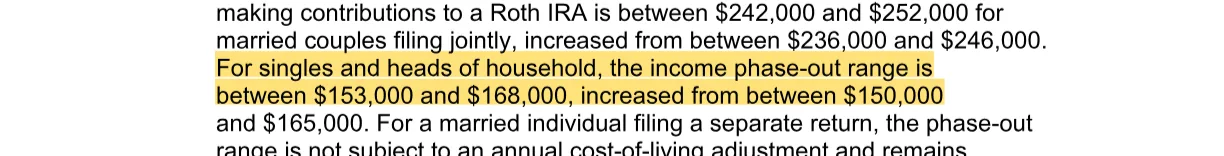
For 2026 the adjusted gross income phase-out range for taxpayers making contributions to a Roth IRA is between $242,000 and $252,000 for married couples filing jointly, increased from between $236,000 and $246,000. For singles and heads of household the range is between $153,000 and $168,000, increased from between $150,000 and $165,000. Both ends of both ranges moved up. Notice 2025-67 reaches them by raising the adjusted gross income limitation under section 408A from $236,000 to $242,000 for a joint return or a qualifying widow(er), and from $150,000 to $153,000 for all other taxpayers other than married taxpayers filing separately.
Common questions
- What is the Roth IRA income limit for 2026 if I file single?
- For 2026 the adjusted gross income phase-out range for singles and heads of household is between $153,000 and $168,000. Below $153,000 the phase-out does not bite. Across the range the maximum Roth IRA contribution is reduced as income rises, and at $168,000 the range is exhausted. Notice 2025-67 sets both ends, working from the adjusted gross income limitation under section 408A.
- What is the Roth IRA income limit for married filing jointly in 2026?
- The range runs between $242,000 and $252,000 of adjusted gross income for 2026, and the same range covers a taxpayer filing as a qualifying widow(er). Notice 2025-67 sets $242,000 as the adjusted gross income limitation under section 408A for a joint return and gives $252,000 as the top of the phase-out range. A couple below $242,000 is outside the phase-out entirely.
- How much did the Roth IRA income limits change for 2026?
- Notice 2025-67 moves the joint range from between $236,000 and $246,000 to between $242,000 and $252,000, and the range for singles and heads of household from between $150,000 and $165,000 to between $153,000 and $168,000. Each end moved separately under the notice's rounding rules, so the two ends of a range do not shift by matching steps.
- What happens if my income is above the Roth IRA phase-out range?
- The range ends at $168,000 for singles and heads of household and at $252,000 for married couples filing jointly. Notice 2025-67 describes these as the adjusted gross income phase-out range for taxpayers making contributions to a Roth IRA, so income at the top of the applicable range leaves nothing of the contribution the limitation would otherwise allow. Between the two ends the amount is reduced rather than removed.
- Do heads of household use the single or the joint Roth IRA range?
- The single range. Notice 2025-67 groups singles and heads of household together and gives them one range for 2026, between $153,000 and $168,000. The range between $242,000 and $252,000 is reserved for married couples filing jointly and for taxpayers filing as a qualifying widow(er). The notice draws no separate head of household figure for Roth IRA contributions.
- What is the Roth IRA income limit for married filing separately?
- Notice 2025-67 states that for a married individual filing a separate return the phase-out range is not subject to an annual cost-of-living adjustment. It therefore stayed where it was for 2026 while the others rose, and it is stated in the notice as its own range, distinct from the $153,000 to $168,000 range for singles and heads of household and from the $242,000 to $252,000 range for joint returns. That range runs from $0 to $10,000 of adjusted gross income.
- What income figure does the Roth IRA limit use?
- Adjusted gross income. Notice 2025-67 states the 2026 amounts as adjusted gross income limitations under section 408A, then restates them as an adjusted gross income phase-out range for taxpayers making contributions to a Roth IRA. That income measure, together with filing status, is what places a taxpayer below, inside, or above the applicable range for the year.
- Where do the 2026 Roth IRA income limits come from?
- Notice 2025-67, titled 2026 Amounts Relating to Retirement Plans and IRAs, as Adjusted for Changes in Cost-of-Living. It states the adjusted gross income limitations under section 408A and then the resulting phase-out ranges for 2026: $242,000 to $252,000 for married couples filing jointly and $153,000 to $168,000 for singles and heads of household, after its rounding rules are applied.
Every amount on this page is a published figure rather than yours. The Roth IRA limit left for a single filer takes the number you enter and works it out against them, showing which published figure it used.
How a high modified AGI reduces the limit
This sentence introduces the income-based phaseout that applies to Roth IRA contributions. When a taxpayer's modified AGI rises above the phaseout threshold for their filing status, the maximum amount they may contribute to a Roth IRA is gradually reduced rather than eliminated all at once. For 2026, the phaseout begins at $153,000 of modified AGI for single filers and at $242,000 for married couples filing jointly. The reduction continues across a range of income and ends completely once modified AGI reaches $168,000 for single filers or $252,000 for joint filers. Taxpayers whose modified AGI falls below the phaseout start may contribute up to the full annual limit. The IRS publishes a table (Table 2-1 in Publication 590-A) that lets contributors look up whether the reduction applies to them based on their filing status and income level.
Contribution limit reduced. If your modified AGI is above a certain amount, your contribution limit is gradually reduced.
Publication 590-A (2025), Contributions to Individual Retirement Arrangements (IRAs) (IRS)
Figuring the reduced limit, and how it is rounded
Once the IRS formula produces a reduced contribution limit, the result is not left as a fractional dollar amount. You must round it up to the next whole multiple of $10. There is also a special floor: if the rounded figure is greater than $0 but falls below $200, the limit is raised to $200 so that a small residual entitlement is not lost entirely. This floor prevents taxpayers with only a tiny remaining contribution room from being left with effectively nothing. If the calculation produces $0, the floor does not apply and no Roth IRA contribution is permitted for the year.
Round your reduced contribution limit up to the nearest $10. If your reduced contribution limit is more than $0, but less than $200, increase the limit to $200.
Publication 590-A (2025), Contributions to Individual Retirement Arrangements (IRAs) (IRS)
The income the test uses is modified AGI
The income test that determines whether your Roth IRA contribution limit is reduced is based on modified AGI, not the regular adjusted gross income shown on page 1 of your tax return. Modified AGI starts with your AGI and then adds back certain items the IRS specifies for this purpose, the most common being income from a Roth conversion. Because conversions can substantially increase the number used for the phase-out, taxpayers who are converting a traditional IRA to a Roth in the same year may find that the conversion itself pushes their modified AGI higher and reduces or eliminates the very contribution room they were trying to use. The IRS provides Worksheet 2-1 to compute the correct modified AGI figure to use in the phase-out calculation.
Modified AGI. Your modified AGI for Roth IRA purposes is your AGI as shown on your return with some adjust- ments. Use Worksheet 2-1 to determine your modified AGI.
Publication 590-A (2025), Contributions to Individual Retirement Arrangements (IRAs) (IRS)
Traditional and Roth contributions share one annual limit
A taxpayer's annual contribution limit is not calculated separately for traditional and Roth IRAs. Instead, there is a single overall limit, and Roth IRA room is what remains after any contributions to traditional IRAs are taken into account. In practice, you first determine what your limit would be if you contributed only to Roth IRAs, and then you subtract from that figure every contribution made for the year to traditional IRAs (other than employer contributions to a SEP or SIMPLE plan). The result is the most you may put into Roth IRAs for the year. This rule means that contributing to a traditional IRA directly reduces the room available for Roth contributions dollar for dollar, up to the overall annual limit.
Roth IRAs and traditional IRAs. If contributions are made to both Roth IRAs and traditional IRAs established for your benefit, your contribution limit for Roth IRAs is generally the same as your limit would be if contributions were made only to Roth IRAs, but then reduced by all con- tributions for the year to all IRAs other than Roth IRAs.
Publication 590-A (2025), Contributions to Individual Retirement Arrangements (IRAs) (IRS)
Contributions for a year can be made up until the filing deadline
In the federal tax system, contributions to a Roth IRA for a given tax year can be made at any point during that calendar year, or after the year ends, up until the filing deadline for that year's federal income tax return, without counting any extension. That means the window for a given year's contributions stays open for several months into the following year, closing on the regular due date for filing that year's return. For example, the window for 2025 contributions closed on April 15, 2026, the regular due date for filing a 2025 return. An extension to file does not extend this contribution deadline; only the actual, unextended due date controls. The annual IRA contribution limit is $7,500, and that is the maximum that can be contributed (subject to income phase-outs) before the deadline for that year's contributions passes.
You can make contributions to a Roth IRA for a year at any time during the year or by the due date of your return for that year (not including extensions). You can make contributions for 2025 by the due date (not including extensions) for filing your 2025 tax return. This means that most people can make contributions for 2025 by April 15, 2026.
Publication 590-A (2025), Contributions to Individual Retirement Arrangements (IRAs) (IRS)
There is no line on your return for a Roth contribution
In the federal tax system, you do not report Roth IRA contributions on your tax return. Unlike traditional IRA contributions, which may be deductible and must be reported to claim the deduction, Roth IRA contributions are made with after-tax dollars and are not deductible. This means there is no line on your return where you enter the amount you contributed to a Roth IRA for the year. The contribution limit for 2026 is $7,500 (plus any catch-up amount if you qualify), but you do not need to track or report these contributions on your federal income tax return. However, you should keep records of your contributions for your own purposes, especially to track your basis in the Roth IRA for future withdrawals.
Contributions not reported. You don’t report Roth IRA contributions on your return.
Publication 590-A (2025), Contributions to Individual Retirement Arrangements (IRAs) (IRS)
An excess contribution can be soaked up by a later year's room
In the federal tax system, if you contribute more than the annual IRA contribution limit of $7,500 (plus any catch-up amount you qualify for) to a Roth IRA for a year, you can apply the excess contribution in one year to a later year if the contributions for that later year are less than the maximum allowed for that year. This means if you have unused contribution room in a future year, you can use it to absorb a prior year's excess contribution. However, this rule does not eliminate the penalty that applies to excess contributions. The excess remains subject to tax until it is either withdrawn or absorbed by unused contribution room in a later year. This provides a way to correct overcontributions over time without requiring an immediate withdrawal, but the penalty continues to accrue during the period the excess remains in the account.
If contributions to your IRA for a year were more than the limit, you can apply the excess contribution in one year to a later year if the contributions for that later year are less than the maximum allowed for that year.
Publication 590-A (2025), Contributions to Individual Retirement Arrangements (IRAs) (IRS)
Contributing more than the limit costs a 6% excise tax
For 2026 in the federal tax system, contributing more than the annual IRA contribution limit of $7,500 (plus any catch-up amount you qualify for) to a Roth IRA triggers a 6% excise tax on the excess amount. The tax applies each year the excess remains in the account. You can avoid the tax in later years by withdrawing the excess or by using a later year's contribution room to absorb it, but the penalty is assessed on Form 5329 and reported with your federal return.
A 6% excise tax applies to any excess contribution to a Roth IRA.
Publication 590-A (2025), Contributions to Individual Retirement Arrangements (IRAs) (IRS)
How each figure was verified
Each number below was read from a stored copy of the document named beside it, and checked to occur word for word in the quoted sentence. The digest is of that stored text.
Notice 2025-67 (IRS)
- Phase-out start, single filers
For singles and heads of household, the income phase-out range is between $153,000 and $168,000
- Phase-out end, single filers
For singles and heads of household, the income phase-out range is between $153,000 and $168,000
- Phase-out start, joint filers
the adjusted gross income phase-out range for taxpayers making contributions to a Roth IRA is between $242,000 and $252,000 for married couples filing jointly
- Phase-out end, joint filers
the adjusted gross income phase-out range for taxpayers making contributions to a Roth IRA is between $242,000 and $252,000 for married couples filing jointly
- Annual IRA contribution limit
The deductible amount under section 219(b)(5)(A), which limits the amount of an individual’s deductible qualified retirement contributions for a taxable year is increased from $7,000 to $7,500.
- Phase-out start, separate filers
For a married individual filing a separate return, the phase-out range is not subject to an annual cost-of-living adjustment and remains between $0 and $10,000.
- Phase-out end, separate filers
For a married individual filing a separate return, the phase-out range is not subject to an annual cost-of-living adjustment and remains between $0 and $10,000.