2027 Premium Tax Credit
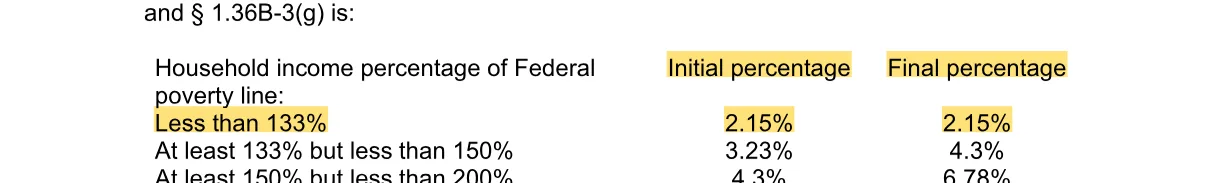
For 2027, the Premium Tax Credit figures are 2.15% (Lowest applicable percentage) and 10.22% (Highest applicable percentage).
Effective 2027-01-01Source: Rev. Proc. 2026-26 (IRS)Verified 2026-09-03
Compared with 2026
| Item | 2026 | 2027 | Change |
|---|---|---|---|
| Lowest applicable percentage | 2.1% | 2.15% | +0.05% (+2.4%) |
| Highest applicable percentage | 9.96% | 10.22% | +0.26% (+2.6%) |
Who it applies to
Individuals and families who purchase health insurance through the Marketplace and qualify for the Premium Tax Credit under IRC § 36B for taxable years beginning in calendar year 2027.
What changed this year, and why
The IRS published the 2027 Applicable Percentage Table used to calculate the Premium Tax Credit under § 36B. The table sets the caps on what eligible households pay toward health insurance premiums, with the credit covering the remainder.
Common questions
- What are the applicable percentages for 2027?
- For taxable years beginning in calendar year 2027, the lowest applicable percentage is 2.15% and the highest applicable percentage is 10.22%.
- How do the 2027 percentages compare with 2026?
- Both the lowest and highest applicable percentages increased for 2027. The lowest rose from 2.1% in 2026 to 2.15% in 2027, and the highest rose from 9.96% in 2026 to 10.22% in 2027.
Who counts as an applicable taxpayer
An applicable taxpayer for the Premium Tax Credit (PTC) is someone who must file Form 8962 with their income tax return (Form 1040, 1040-SR, or 1040-NR) if any of the following conditions apply: they are taking the PTC; advance premium tax credit (APTC) was paid for them or another individual in their tax family; or APTC was paid for an individual they told the Marketplace would be in their tax family and neither they nor anyone else included that individual in a tax family. If any of these circumstances apply, the taxpayer must file an income tax return and attach Form 8962 even if they are not otherwise required to file. They cannot file Form 1040-SS. If someone else enrolled an individual in the taxpayer's tax family in coverage and APTC was paid for that individual's coverage, the taxpayer must file Form 8962 to reconcile the APTC. However, if the taxpayer is claimed as a dependent on another person's tax return, the person who claims them will file Form 8962 to take the PTC and repay excess APTC if necessary, and the dependent does not need to file Form 8962.
You must file Form 8962 with your income tax return (Form 1040, 1040-SR, or 1040-NR) if any of the following apply to you. • You are taking the PTC. • APTC was paid for you or another individual in your tax family. • APTC was paid for an individual you told the Marketplace would be in your tax family and neither you nor anyone else included that individual in a tax family.
2025 Instructions for Form 8962, Premium Tax Credit (IRS)
Household income is not the same as your AGI
Household income for the Premium Tax Credit is not the same as your adjusted gross income (AGI). Instead, it is the modified adjusted gross income (modified AGI) of you and your spouse (if filing a joint return), plus the modified AGI of each dependent who is required to file a tax return because their income meets the filing threshold. Modified AGI is your AGI plus certain untaxed income such as foreign earned income, tax-exempt interest, and the non-taxable portion of social security benefits. Importantly, household income does not include the modified AGI of dependents who file a return only to claim a refund of withheld or estimated tax. This means that even if your AGI is below the federal poverty line, adding certain untaxed income or the income of dependents could push your household income above it, affecting your eligibility for the credit.
Household income. For purposes of the PTC, household income is the modified adjusted gross income (modified AGI) of you and your spouse (if filing a joint return) (see Line 2a, later) plus the modified AGI of each individual whom you claim as a dependent and who is required to file an income tax return because their income meets the income tax return filing threshold (see Line 2b, later).
2025 Instructions for Form 8962, Premium Tax Credit (IRS)
The second lowest cost silver plan sets the credit
The premium tax credit is based on the cost of a specific plan called the second lowest cost silver plan (SLCSP). This is the silver-level plan with the second-lowest premium offered through the Marketplace in your area that covers your tax family. Your credit amount is calculated using this benchmark plan's premium, not the premium you actually pay for your enrollment plan. If you happen to enroll in the SLCSP itself, then your enrollment premium equals the benchmark premium, but in most cases they differ. Form 1095-A, Part III, column B, reports the applicable SLCSP premium, though it may be wrong or blank if you had unreported changes in circumstances or if no advance credit was paid. The difference between the benchmark premium and your required contribution (based on your household income and the applicable percentage, which ranges from the lowest of 2.15% to the highest of 10.22%) determines your monthly credit amount.
Applicable SLCSP premium. The applicable SLCSP premium is the second lowest cost silver plan premium offered through the Marketplace where you reside that applies to your coverage family (described earlier).
2025 Instructions for Form 8962, Premium Tax Credit (IRS)
OBBBA removed the income-based cap on paying back advance credit
Section 71305 of the One, Big, Beautiful Bill Act removed § 36B(f)(2)(B) from the tax code, so there is no longer an income-based cap on repaying excess advance premium tax credit. That subsection used to limit how much a lower-income household had to pay back when its actual income came in higher than it estimated when it enrolled. For 2027, exactly as for 2026, if you received more advance payments of the premium tax credit than you turn out to be entitled to, you repay the full excess amount when you reconcile on Form 8962, no matter how low your household income is.
Section 71305 of the OBBBA removes § 36B(f)(2)(B), which limited the tax increase from excess advance payments for certain households
Rev. Proc. 2025-32 (IRS)
Filing separately usually disqualifies you
If you are married at the end of the tax year, you generally must file a joint return with your spouse to be eligible for the premium tax credit. This requirement applies even if you and your spouse lived apart during the year. Filing a separate return usually disqualifies you from claiming the credit. However, the IRS provides two exceptions. The first exception is for married persons living apart who qualify to file as head of household, meaning you lived apart from your spouse for the last half of the year, maintained a household for a qualifying child, and meet the related requirements. The second exception is for victims of domestic abuse or spousal abandonment. If either exception applies, you may take the credit without filing jointly. If neither exception applies, you cannot take the premium tax credit unless you and your spouse file a joint return together.
Married taxpayers. If you are considered married for federal income tax purposes, you must file a joint return with your spouse to take the PTC unless one of the two exceptions below applies to you.
2025 Instructions for Form 8962, Premium Tax Credit (IRS)
A change in income or family should be reported right away, not held for tax time
Taxpayers who receive advance payments of the premium tax credit (APTC) must promptly report life changes - such as shifts in household income or family size - to the Marketplace where they enrolled, rather than waiting until tax filing season. These adjustments matter because APTC is calculated using projections made at enrollment; if actual income or family composition changes during the year and the Marketplace is not notified, the advance payments may not match the credit the taxpayer is ultimately entitled to claim. Reporting updates allows the Marketplace to revise the amount of APTC sent to the insurer on the taxpayer's behalf, helping to reduce the risk of either owing money back at reconciliation or missing out on credit they were eligible for. This ongoing obligation applies throughout the coverage year, not only at the time of re-enrollment.
Report changes in circumstances when you re-enroll in coverage and during the year. If advance payment of the premium tax credit (APTC) is being paid for an individual in your tax family (described later) and you have had certain changes in circumstances (see the examples later), it is important that you report them to the Marketplace where you enrolled in coverage. Reporting changes in circumstances promptly will allow the Marketplace to adjust
2025 Instructions for Form 8962, Premium Tax Credit (IRS)
APTC forces a return even when your income wouldn't otherwise require one
The premium tax credit reconciliation requires a tax return even when a taxpayer's income would not otherwise call for one. If any of several conditions exist - such as receiving advance payments of the credit, having an individual in the tax family who received advance payments, or being claimed as a dependent - the taxpayer must file a federal income tax return and attach Form 8962 to complete the year-end calculation of the credit. The rule applies regardless of whether gross income meets the normal filing threshold, because the form is the only way to match the advance payments already sent to the insurer against the credit the taxpayer actually qualifies for based on final household income and family size for the year. The taxpayer must use the standard individual income tax return; certain simplified filing forms are not accepted when the reconciliation form is required.
If any of the circumstances above apply to you, you must file an income tax return and attach Form 8962 even if you are not otherwise required to file.
2025 Instructions for Form 8962, Premium Tax Credit (IRS)
An affordable QSEHRA from your employer can wipe out the credit for that month
When a taxpayer is covered under a qualified small employer health reimbursement arrangement, the affordability of the arrangement determines whether the taxpayer may claim any premium tax credit at all for that month. If the employer's QSEHRA is considered affordable for a given month, the taxpayer is treated as having affordable employer coverage for that month and is ineligible for the credit - no premium tax credit is allowed. If the arrangement is unaffordable for a month, the taxpayer may claim a reduced credit, with the monthly permitted benefit amount subtracted from what would otherwise be due. The employer reports the permitted benefit amount on the employee's Form W-2. Taxpayers with an affordable QSEHRA should not expect to receive a premium tax credit for those months and should note the arrangement on Form 8962 to avoid processing delays.
If the QSEHRA is affordable for a month, no PTC is allowed for the month.
2025 Instructions for Form 8962, Premium Tax Credit (IRS)
A wrong benchmark premium on your Form 1095-A does not excuse using it
The second-lowest-cost silver plan premium from Form 1095-A drives the benchmark used to work out the premium tax credit, and taxpayers may not simply accept the figure printed on the form when they suspect it is wrong. If a taxpayer has reason to believe the Marketplace reported the wrong applicable second-lowest-cost silver plan premium, the taxpayer must determine the correct applicable premium for every month of the year, not just the months in question. When the correct benchmark premium differs across months, the taxpayer checks "No" on the appropriate line and works through the monthly calculation on the return. The two most common situations where the form's premium may not reflect the correct benchmark are months where no advance payments were paid for the coverage and months where the Marketplace's published rate table differed from what appeared on the form. The burden to identify and use the correct figure rests with the taxpayer.
If either of these two situations applies to you, or if you have reason to believe the Marketplace reported the wrong applicable SLCSP premium, you must determine the correct applicable SLCSP premium for every month.
2025 Instructions for Form 8962, Premium Tax Credit (IRS)
How each figure was verified
Each number below was read from a stored copy of the document named beside it, and checked to occur word for word in the quoted sentence. The digest is of that stored text.
Rev. Proc. 2026-26 (IRS)
- Lowest applicable percentage
Initial percentage Final percentage Less than 133% 2.15% 2.15%
- Highest applicable percentage
At least 300% but not more than 400% 10.22% 10.22%