2026 FUTA Tax Rate & Wage Base
For 2026, the FUTA Tax Rate & Wage Base figures are $7,000 (Wage base) and 0.6% (Net FUTA rate after the maximum state credit).
Effective 2026-01-01Source: Publication 15 (2026), (Circular E), Employer's Tax Guide (IRS)Verified 2026-09-03
Compared with 2025
Every figure on this page is unchanged from 2025.
| Item | 2025 | 2026 | Change |
|---|---|---|---|
| Wage base | $7,000 | $7,000 | +$0 (+0.0%) |
| Net FUTA rate after the maximum state credit | 0.6% | 0.6% | +0% (+0.0%) |
Who it applies to
FUTA is an employer tax. Publication 15 says only the employer pays FUTA tax and that it is not withheld from the employee's wages. The guide gives three independent tests, each covering a different category of employee. Under the general test you are subject to FUTA tax in 2026 if you paid wages of at least the quarterly amount the guide states in any calendar quarter in 2025 or 2026, or if you had one or more employees for at least some part of a day in as many different weeks as the guide specifies in either year. The household employees test is measured by total cash wages paid to household employees in a calendar quarter, and the farmworkers test by cash wages paid to farmworkers in a calendar quarter or by the number of farmworkers employed in enough different weeks. Wages paid to H-2A visa workers count when you decide whether the farmworker test is met, but those wages are not themselves subject to FUTA tax.
What changed this year, and why
The FUTA wage base for 2026 is $7,000, the same amount that applied for 2025. Publication 15 (2026), the Employer's Tax Guide, states it in section 14: the FUTA tax applies to the first $7,000 you pay to each employee as wages during the year, and that $7,000 is the federal wage base. Nothing in the What's New items for 2026 touches it. Those items cover the social security and Medicare tax rates and the social security wage base limit, the permanent extension of the individual income tax rates by the One Big Beautiful Bill Act and what it means for supplemental wage and backup withholding, the raised information reporting thresholds, and the new withholding treatment of qualified tips and overtime. The Reminders add that an amended Form 940 can now be filed electronically through Modernized e-File. The guide also warns that a state wage base limit may be different from the federal one, and that the credit an employer takes for state unemployment contributions, together with any credit reduction the U.S. Department of Labor determines for a state, changes what the employer owes rather than the wages the tax is measured on.
Common questions
- What is the FUTA wage base for 2026?
- It is $7,000. Publication 15 (2026) says the FUTA tax applies to the first $7,000 you pay to each employee as wages during the year, and calls that $7,000 the federal wage base. Wages you pay the same employee above that point later in the calendar year are not part of the FUTA taxable wages you carry to Form 940.
- Did the FUTA wage base change from 2025 to 2026?
- No. It was $7,000 for 2025 and it is $7,000 for 2026. The amount is set by statute rather than adjusted for inflation each year, so it does not move with the annual inflation adjustments that change most other payroll and tax figures.
- Is the $7,000 measured per employee or per employer?
- Per employee, and each employer applies it to its own payroll. Publication 15 gives one exception: a successor employer who acquired a business from an employer who was liable for FUTA tax may count the wages that employer paid to employees who continue to work for the successor when figuring the $7,000 FUTA tax wage base limit.
- Does my state use the same $7,000 wage base?
- Not necessarily. Publication 15 says your state wage base limit may be different from the federal one. It adds that in some states the wages subject to state unemployment tax are the same as the wages subject to FUTA tax, while other states exclude some types of wages, such as wages paid to corporate officers or certain payments of sick pay by unions, from state unemployment tax even though those wages are subject to FUTA tax.
- When do I stop depositing FUTA tax for an employee?
- Publication 15 says to stop depositing FUTA tax on an employee's wages when taxable wages reach $7,000 for the calendar year. For deposit purposes FUTA tax is figured quarterly, and a deposit is due by the last day of the first month that follows the end of the quarter, moving to the next business day when that date falls on a Saturday, Sunday, or legal holiday.
- Which form reports FUTA tax?
- Form 940, the Employer's Annual Federal Unemployment (FUTA) Tax Return. Publication 15 says to use Form 940 to report FUTA tax. Household employers who did not report employment taxes for household employees on Form 941, Form 943, or Form 944 report FUTA tax for those employees on Schedule H (Form 1040) instead, and they need an EIN to file it.
- Does the FUTA wage base change what an employer actually owes?
- It sets the wages the tax is measured on, and the credit for state unemployment contributions then sets most of what is left. Publication 15 says an employer generally takes a credit against FUTA tax for amounts paid into state unemployment funds, and is entitled to the maximum credit when state unemployment taxes were paid in full, on time, and on all the same wages subject to FUTA tax, as long as the state is not determined to be a credit reduction state.
Every amount on this page is a published figure rather than yours. The FUTA wage base headroom takes the number you enter and works it out against them, showing which published figure it used.
The $1,500 quarter test and the 20 week test
An employer must file Form 940 for 2025 if it meets either of two tests during 2024 or 2025. The first test looks at wages: if the employer paid $1,500 or more in wages to employees in any single calendar quarter, the filing threshold is met. The second test looks at duration: if the employer had one or more employees for at least some part of a day in 20 or more different weeks, the threshold is met. When counting weeks for the second test, all full-time, part-time, and temporary employees are included, but partners in a partnership are not counted. Answering "Yes" to either question means the employer must file. The FUTA tax itself applies only to the first $7,000 paid to each employee during the calendar year, after subtracting any payments that are exempt from FUTA tax.
Who Must File Form 940? Except as noted below, if you answer “Yes” to either one of these questions, you must file Form 940. • Did you pay wages of $1,500 or more to employees in any calendar quarter during 2024 or 2025? • Did you have one or more employees for at least some part of a day in any 20 or more different weeks in 2024 or 20 or more different weeks in 2025? Count all full-time, part-time, and temporary employees.
2025 Instructions for Form 940, Employer’s Annual Federal Unemployment (FUTA) Tax Return (IRS)
The rate charged on the wage base, and the state credit against it
For 2026 the federal unemployment tax (FUTA) rate is 6.0%. That rate applies only to the first $7,000 of wages paid to each employee during the year - amounts above that threshold are not taxed. Employers generally receive a credit of up to 5.4% of FUTA-taxable wages for contributions they make to state unemployment funds. When the full 5.4% credit is available, the effective federal rate drops to 0.6%. The maximum credit is available as long as the employer paid state unemployment taxes in full and on time, on the same wages subject to FUTA, and the employer's state has not been classified as a credit-reduction state. In many states the wages subject to the state unemployment tax match those subject to FUTA, but some states exclude certain types of wages, which can affect the credit calculation.
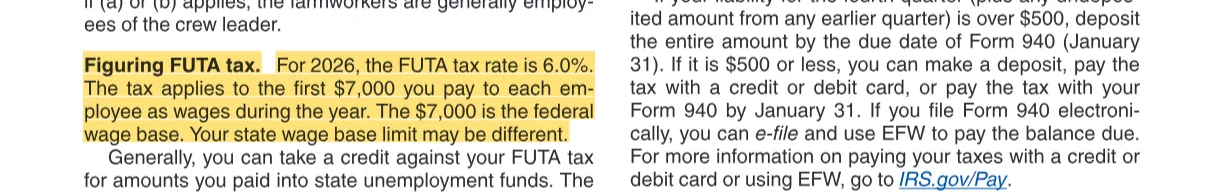
For 2026, the FUTA tax rate is 6.0%. The tax applies to the first $7,000 you pay to each em- ployee as wages during the year. The $7,000 is the federal wage base. Your state wage base limit may be different. Generally, you can take a credit against your FUTA tax for amounts you paid into state unemployment funds. The credit may be as much as 5.4% of FUTA taxable wages. If you’re entitled to the maximum 5.4% credit, the FUTA tax rate after credit is 0.6%.
Publication 15 (2026), (Circular E), Employer's Tax Guide (IRS)
Why employers in some states pay more
Employers in certain states pay more federal unemployment tax when those states have not repaid federal loans used to fund their unemployment programs. For 2025, California and the U.S. Virgin Islands are subject to credit reduction, meaning employers in those jurisdictions lose part of the normal FUTA tax credit they would otherwise receive. The credit reduction rate for California is 0.012 (1.2%), and for the U.S. Virgin Islands it is 0.045 (4.5%). These rates are applied to FUTA taxable wages paid in those states, up to the federal wage base of $7,000. Wages that were excluded from state unemployment tax are not included when calculating the additional tax. Employers must report the FUTA taxable wages paid in each credit reduction state and calculate the additional tax owed using Schedule A (Form 940). This additional amount is added to the employer's regular FUTA tax liability.
Credit reduction states for 2025. The credit reduction rate for California is 0.012 (1.2%). The credit reduction rate for the U.S. Virgin Islands is 0.045 (4.5%).
Schedule A (Form 940) for 2025, Multi-State Employer and Credit Reduction Information (IRS)
Household employers are tested separately
Household employers are subject to different filing thresholds than other employers. A household employer must pay FUTA tax on wages paid to household employees only if the employer paid cash wages of $1,000 or more in any calendar quarter in 2024 or 2025. This dollar threshold is lower than the general quarterly test that applies to other employers. A household employee performs household work in a private home, local college club, or local chapter of a college fraternity or sorority. Generally, employers of household employees must file Schedule H (Form 1040) instead of Form 940. However, if the household employer has other employees in addition to household employees, the employer can choose to include the FUTA taxes for household employees on Form 940 instead of filing Schedule H. Household employers are tested separately, meaning the $1,000 quarterly threshold applies only to household employee wages and does not combine with wages paid to other types of employees.
If you’re a household employer, you must pay FUTA tax on wages that you paid to your household employees only if you paid cash wages of $1,000 or more in any calendar quarter in 2024 or 2025.
2025 Instructions for Form 940, Employer’s Annual Federal Unemployment (FUTA) Tax Return (IRS)
The $500 rule that decides when you deposit
Although Form 940 covers a calendar year, employers may have to deposit FUTA tax before filing the return. If your FUTA tax is more than $500 for the calendar year, you must deposit at least one quarterly payment. You must determine when to deposit based on your quarterly tax liability. If your FUTA tax is $500 or less in a quarter, you carry it over to the next quarter. You continue carrying your tax liability over until your cumulative tax is more than $500. At that point, you must deposit your tax for the quarter by the last day of the month after the end of the quarter. If your tax for the next quarter is $500 or less, you're not required to deposit again until the cumulative amount exceeds $500. For fourth quarter liabilities, if your FUTA tax for the fourth quarter plus any undeposited amounts from earlier quarters is more than $500, you must deposit the entire amount by the due date of Form 940. The $500 threshold determines whether you must make quarterly deposits or can wait until you file your annual return.
If your FUTA tax is more than $500 for the calendar year, you must deposit at least one quarterly payment. You must determine when to deposit your tax based on the amount of your quarterly tax liability. If your FUTA tax is $500 or less in a quarter, carry it over to the next quarter.
2025 Instructions for Form 940, Employer’s Annual Federal Unemployment (FUTA) Tax Return (IRS)
Deposits have to be electronic, not mailed
All federal tax deposits, including FUTA tax, must be made electronically using the Electronic Federal Tax Payment System (EFTPS), IRS Direct Pay, or the IRS business tax account. Paper checks mailed to the IRS are not accepted as a deposit. If an employer does not wish to use one of these methods directly, the employer may arrange for a tax professional, financial institution, payroll service, or other trusted third party to make the electronic deposit on the employer's behalf. A financial institution may also be asked to initiate a same-day wire payment. Employers should enroll in EFTPS well in advance of the first deposit deadline to avoid late-deposit penalties.
You must use EFT to make all federal tax deposits. An EFT can be made using EFTPS, IRS Direct Pay, or your IRS business tax account.
2025 Instructions for Form 940, Employer’s Annual Federal Unemployment (FUTA) Tax Return (IRS)
An overpayment is not lost: refund it or apply it forward
If an employer deposits more FUTA tax than is due for the year, the overpayment is not forfeited. On line 15b of Form 940, the employer chooses to have the overpayment either applied to the next year's return or refunded. If the employer wants a refund, lines 15c through 15e must be completed for direct deposit. Only one box may be checked on line 15b. If neither box is checked, or if both boxes are checked, the IRS will generally apply the overpayment to the next return. Regardless of the choice made, the IRS may apply the overpayment to any past-due tax account the employer owes.
Apply the overpayment to your next return, or • Send you a refund (complete lines 15c–15e for direct deposit). Check the appropriate box on line 15b to tell us which option you select.
2025 Instructions for Form 940, Employer’s Annual Federal Unemployment (FUTA) Tax Return (IRS)
Filing with the wrong EIN can cost you penalties, not just a processing delay
The EIN on Form 940 must exactly match the EIN the IRS assigned to the business. Filing the return with an incorrect EIN, or using the EIN of another business, may result in penalties and delays in processing the return. A return filed with an invalid EIN may not be accepted at all. Employers should verify that the EIN on the form matches IRS records before filing. A social security number or individual taxpayer identification number must not be used in place of an EIN. Disregarded entities must file using their own name and EIN, not the name and EIN of the owner.
Filing a Form 940 with an incorrect EIN or using the EIN of another’s business may result in penalties and delays in processing your return.
2025 Instructions for Form 940, Employer’s Annual Federal Unemployment (FUTA) Tax Return (IRS)
How each figure was verified
Each number below was read from a stored copy of the document named beside it, and checked to occur word for word in the quoted sentence. The digest is of that stored text.
Publication 15 (2026), (Circular E), Employer's Tax Guide (IRS)
- Wage base
Figuring FUTA tax. For 2026, the FUTA tax rate is 6.0%. The tax applies to the first $7,000 you pay to each em- ployee as wages during the year. The $7,000 is the federal wage base.
- Net FUTA rate after the maximum state credit
If you’re entitled to the maximum 5.4% credit, the FUTA tax rate after credit is 0.6%.