2026 Earned Income Tax Credit
For 2026, the Earned Income Tax Credit figures are $4,427 (Maximum credit, one child), $7,316 (Maximum credit, two children), $8,231 (Maximum credit, three or more children) and 21 more figures below.
| Item | One child | Two children | Three or more children | Childless filers |
|---|---|---|---|---|
| Maximum credit | $4,427 | $7,316 | $8,231 | $664 |
| Earned income amount | $13,020 | $18,290 | $18,290 | $8,680 |
| Phaseout begins (not filing jointly) | $23,890 | $23,890 | $23,890 | $10,860 |
| Phaseout begins (joint return) | $31,160 | $31,160 | $31,160 | $18,140 |
| Credit reaches zero (not filing jointly) | $51,593 | $58,629 | $62,974 | $19,540 |
| Credit reaches zero (joint return) | $58,863 | $65,899 | $70,244 | $26,820 |
Effective 2026-01-01Source: Rev. Proc. 2025-32 (IRS)Verified 2026-09-03
Compared with 2025
| Item | 2025 | 2026 | Change |
|---|---|---|---|
| Maximum credit, one child | $4,328 | $4,427 | +$99 (+2.3%) |
| Maximum credit, two children | $7,152 | $7,316 | +$164 (+2.3%) |
| Maximum credit, three or more children | $8,046 | $8,231 | +$185 (+2.3%) |
| Maximum credit, childless filers | $649 | $664 | +$15 (+2.3%) |
| Earned income amount, one child | $12,730 | $13,020 | +$290 (+2.3%) |
| Earned income amount, two children | $17,880 | $18,290 | +$410 (+2.3%) |
| Earned income amount, three or more children | $17,880 | $18,290 | +$410 (+2.3%) |
| Earned income amount, childless filers | $8,490 | $8,680 | +$190 (+2.2%) |
| Phaseout begins (not filing jointly), one child | $23,350 | $23,890 | +$540 (+2.3%) |
| Phaseout begins (not filing jointly), two children | $23,350 | $23,890 | +$540 (+2.3%) |
| Phaseout begins (not filing jointly), three or more children | $23,350 | $23,890 | +$540 (+2.3%) |
| Phaseout begins (not filing jointly), childless filers | $10,620 | $10,860 | +$240 (+2.3%) |
| Phaseout begins (joint return), one child | $30,470 | $31,160 | +$690 (+2.3%) |
| Phaseout begins (joint return), two children | $30,470 | $31,160 | +$690 (+2.3%) |
| Phaseout begins (joint return), three or more children | $30,470 | $31,160 | +$690 (+2.3%) |
| Phaseout begins (joint return), childless filers | $17,730 | $18,140 | +$410 (+2.3%) |
| Credit reaches zero (not filing jointly), one child | $50,434 | $51,593 | +$1,159 (+2.3%) |
| Credit reaches zero (not filing jointly), two children | $57,310 | $58,629 | +$1,319 (+2.3%) |
| Credit reaches zero (not filing jointly), three or more children | $61,555 | $62,974 | +$1,419 (+2.3%) |
| Credit reaches zero (not filing jointly), childless filers | $19,104 | $19,540 | +$436 (+2.3%) |
| Credit reaches zero (joint return), one child | $57,554 | $58,863 | +$1,309 (+2.3%) |
| Credit reaches zero (joint return), two children | $64,430 | $65,899 | +$1,469 (+2.3%) |
| Credit reaches zero (joint return), three or more children | $68,675 | $70,244 | +$1,569 (+2.3%) |
| Credit reaches zero (joint return), childless filers | $26,214 | $26,820 | +$606 (+2.3%) |
Maximum credit
Earned income amount
Phaseout begins (not filing jointly)
Phaseout begins (joint return)
Credit reaches zero (not filing jointly)
Credit reaches zero (joint return)
$664$70,244
One dot per column of the table, on a scale running from the smallest of these amounts to the largest. The scale is logarithmic - each faint line is ten times the one before it, so that the amounts crowded at the low end stay far enough apart to read. The table states which dot is which.
Who it applies to
The earned income credit goes to individual taxpayers with earned income, and what they can claim turns on the number of qualifying children and on filing status. For taxable years beginning in 2026 the maximum credit is $8,231 with three or more qualifying children and $664 with none, and Rev. Proc. 2025-32 states separate maximums for one qualifying child and for two. Earnings matter in both directions. The earned income amount is the level of earned income at or above which the maximum credit is allowed, so lower earnings produce a smaller credit. Above the threshold phaseout amount the credit begins to fall, and at or above the completed phaseout amount none is allowed. The phaseout amounts shown for married taxpayers filing a joint return include the increase provided in § 32; those shown for all other filing statuses also apply to married taxpayers not filing jointly who satisfy the special rules for separated spouses in § 32.
What changed this year, and why
The maximum earned income credit rose for taxable years beginning in 2026. For a taxpayer with three or more qualifying children it goes from $8,046 to $8,231, and for a taxpayer with no qualifying children from $649 to $664. Rev. Proc. 2025-32 also restates the other amounts used to determine the credit under § 32 for each family size: the earned income amount, the threshold phaseout amount and the completed phaseout amount, each given once for married taxpayers filing a joint return and once for all other filing statuses. The structure of the credit is unchanged; the amounts are the annual inflation adjustment.
Common questions
- What is the maximum earned income tax credit for 2026?
- For taxable years beginning in 2026, the largest maximum credit Rev. Proc. 2025-32 states under § 32 is $8,231, for a taxpayer with three or more qualifying children. A taxpayer with no qualifying children has a maximum credit of $664. The revenue procedure states separate maximum amounts for one qualifying child and for two, which fall between those two figures.
- How much did the EITC go up for 2026?
- The maximum credit for three or more qualifying children moved from $8,046 to $8,231, and the maximum for a taxpayer with no qualifying children moved from $649 to $664. The earned income amounts and both phaseout amounts were adjusted as well. These are inflation adjustments under Rev. Proc. 2025-32, generally determined by reference to § 1(f), not a change to how the credit is calculated.
- What is the maximum EITC with no children in 2026?
- It is $664 for taxable years beginning in 2026, up from $649 for the prior year. That maximum is reached only at or above the earned income amount stated for the column covering taxpayers with no qualifying children. Childless filers also have their own threshold phaseout and completed phaseout amounts, both lower than the corresponding amounts for taxpayers with qualifying children.
- How much is the 2026 EITC for a family with three or more children?
- The maximum credit is $8,231 for taxable years beginning in 2026. Rev. Proc. 2025-32 uses a single column for three or more qualifying children, so a fourth or fifth child does not push the ceiling above $8,231. Reaching the maximum requires earned income at or above the earned income amount for that column, and keeping it requires income below the threshold phaseout amount.
- Do I need a minimum income to get the full earned income credit?
- Yes. Rev. Proc. 2025-32 defines the earned income amount as the amount of earned income at or above which the maximum amount of the earned income credit is allowed. Below that level the credit is reduced, so a taxpayer with three or more qualifying children will not reach $8,231, and a childless taxpayer will not reach $664, on very low earnings.
- At what income does the 2026 earned income credit phase out?
- The revenue procedure gives two points for every family size and filing status. The threshold phaseout amount is the adjusted gross income, or earned income if greater, above which the maximum credit begins to phase out. The completed phaseout amount is the adjusted gross income, or earned income if greater, at or above which no credit is allowed. Joint filers have higher amounts than other statuses.
- Does investment income affect the EITC in 2026?
- Yes. Rev. Proc. 2025-32 states that for taxable years beginning in 2026 the earned income tax credit is not allowed under § 32 if the aggregate amount of certain investment income exceeds the limit set for the year. That test works as a cliff rather than a phaseout: once it is exceeded no credit is allowed, regardless of earned income or the number of qualifying children.
- Where do the 2026 earned income credit amounts come from?
- From the earned income credit section of Rev. Proc. 2025-32, which modifies Rev. Proc. 2024-40 and states inflation-adjusted items for 2026 for the Code as in effect on October 9, 2025. That section sets the maximum credit of $8,231 and $664 among other amounts, and notes that the instructions for the Form 1040 series provide tables showing the credit for each type of taxpayer.
Every amount on this page is a published figure rather than yours. The EITC with 1 child, not filing jointly takes the number you enter and works it out against them, showing which published figure it used.
Married filing jointly gets a higher phaseout range
Married taxpayers filing a joint return receive higher phaseout thresholds and completed phaseout amounts than other filers. This means a married couple filing jointly can earn more before their credit begins to shrink and before it reaches zero entirely. For 2026 the threshold phaseout amounts for joint filers are $31,160 for one, two, or three-or-more children and $18,140 for childless filers. The completed phaseout amounts for joint filers are $58,863 for one child, $65,899 for two children, $70,244 for three or more children, and $26,820 for childless filers. These joint amounts include an inflation-adjusted increase provided by § 32(b)(2)(B). By contrast, all other filing statuses have thresholds of $23,890 for one, two, or three-or-more children and $10,860 for childless filers, with completed phaseout amounts of $51,593, $58,629, $62,974, and $19,540 respectively. The higher joint range recognizes that married couples often combine their earnings and need a broader income band to receive comparable credit amounts.
Threshold Phaseout Amount (Married Filing Jointly) $31,160 $31,160 $31,160 $18,140 Completed Phaseout Amount (Married Filing Jointly) $58,863 $65,899 $70,244 $26,820 Threshold Phaseout Amount (All other filing statuses) $23,890 $23,890 $23,890 $10,860 Completed Phaseout Amount (All other filing statuses) $51,593 $58,629 $62,974 $19,540
Rev. Proc. 2025-32 (IRS)
Too much investment income disqualifies you outright
Taxpayers whose investment income is too high are disqualified from the earned income credit entirely, regardless of how much earned income they have or how many qualifying children they claim. For taxable years beginning in 2026, the credit is not allowed if aggregate investment income exceeds $12,200. Investment income includes interest, dividends, capital gains, rental and royalty income, and other passive income items. This limit acts as an absolute screen: if a taxpayer's investment income crosses the $12,200 line, the credit is zero even if the taxpayer would otherwise qualify based on earned income and adjusted gross income. The threshold is indexed for inflation and applies uniformly across all filing statuses and family sizes. Taxpayers who are close to the limit should review their investment income carefully, because even a small amount above $12,200 eliminates the credit completely rather than reducing it gradually.
investment income exceeds $12,200.
Rev. Proc. 2025-32 (IRS)
The IRS publishes a lookup table, and that is what you file from
The amount of earned income credit you enter on your 2026 return is read off a table rather than worked out on the form. The instructions for the Form 1040 series print the credit for each type of taxpayer, so that two filers with the same earnings and the same number of qualifying children put down the same figure. What those tables trace is the curve the amounts on this page describe: the credit climbs as earnings rise until it reaches the earned income amount, holds flat at the maximum, then falls away to nothing at the amount where the phaseout is complete, with its own pair of turning points for a joint return. The calculators on this page run that same curve from those same published figures, which is how they can tell you roughly what the credit comes to before you file. The table in the instructions is still the figure you write on the return, because that is the version the IRS reads your return against.
The instructions for the Form 1040 series provide tables showing the amount of the earned income credit for each type of taxpayer.
Rev. Proc. 2025-32 (IRS)
The phaseout is measured on whichever is higher: your AGI or your earnings, and it shrinks gradually rather than falling off a cliff
For the 2026 federal Earned Income Tax Credit, the phaseout does not start at the same point for every taxpayer. Instead, the IRS compares your adjusted gross income with your earned income and uses whichever figure is higher as the starting line. Once that higher amount passes the threshold phaseout amount, the credit begins to shrink. It does not disappear all at once; the credit declines gradually as income rises further, until it reaches the completed phaseout amount, at which point no credit remains. This "whichever is higher" rule means that a taxpayer whose earned income exceeds their AGI cannot escape the phaseout by pointing to a lower AGI, and a taxpayer whose AGI exceeds their earned income cannot avoid it by pointing to lower wages. The 2026 amounts for one child, two children, three or more children, and childless filers are all calculated under this same phaseout structure.
The "threshold phaseout amount" is the amount of adjusted gross income (or, if greater, earned income) above which the maximum amount of the credit begins to phase out.
Rev. Proc. 2025-32 (IRS)
Your earnings have to reach a floor before the credit maxes out, then it holds flat until the phaseout begins
For the 2026 federal Earned Income Tax Credit, a taxpayer's earned income must reach a specific floor before the credit reaches its maximum size. Below that floor, the credit grows as earnings grow; once earnings hit the earned income amount, the credit stops rising and holds flat at the maximum. For 2026, the earned income amount is $13,020 for one qualifying child, $18,290 for two qualifying children, $18,290 for three or more qualifying children, and $8,680 for filers with no qualifying children. The maximum credit then remains at $4,427, $7,316, $8,231, or $664, respectively, until the phaseout begins. This flat plateau means that a worker whose earnings already exceed the earned income amount does not lose anything by earning a little more, up to the point where the phaseout starts; only income above the threshold phaseout amount begins to reduce the credit.
The "earned income amount" is the amount of earned income at or above which the maximum amount of the earned income credit is allowed.
Rev. Proc. 2025-32 (IRS)
Getting a valid SSN after your filing deadline is too late to amend for that year
To claim the 2026 Earned Income Tax Credit, you (and your spouse if filing jointly) must have a valid Social Security Number issued by the Social Security Administration by the due date of your return, including extensions. If you receive a valid SSN after that deadline passes, you cannot amend your return later that year to claim the credit based on that number. The same timing rule applies to any qualifying child whose SSN you need to claim a higher credit amount. A child must have a valid SSN issued on or before the filing deadline for you to claim the credit based on that child. If your child doesn't have a valid SSN by the due date, you may still qualify for a smaller self-only credit if you meet all other requirements, but you cannot claim the higher amounts for that child ($4,427 for one child, $7,316 for two children, or $8,231 for three or more children) or the childless filer amount of $664 based on that child.
Your qualifying child must have a valid SSN issued on or before the due date of your return (including exten- sions) for you to claim a higher EIC amount based on that child.
Publication 596 (2025), Earned Income Credit (IRS)
If the credit is bigger than the tax you owe, you get the difference back
If the Earned Income Tax Credit amount is larger than the tax you owe, you receive the difference as a refund. If you owe no tax at all, you can still receive the full credit as a refund payment. For 2026, the maximum credit amounts are $4,427 for one qualifying child, $7,316 for two qualifying children, $8,231 for three or more qualifying children, and $664 for eligible childless filers. This is what makes the EIC particularly valuable for working people with low to moderate income.
The EIC may also give you a refund.
Publication 596 (2025), Earned Income Credit (IRS)
Getting the EIC does not hurt your eligibility for other federal benefit programs
Any refund you receive because of the Earned Income Tax Credit cannot be counted as income when determining your eligibility for federal, state, or local benefit programs that are financed in whole or in part with federal funds. This includes programs such as Temporary Assistance for Needy Families (TANF), Medicaid, Supplemental Security Income (SSI), Supplemental Nutrition Assistance Program (food stamps), and low-income housing. This protection applies regardless of the credit amount you receive, whether it is $664 for childless filers or $8,231 for families with three or more children.
EIC has no effect on certain welfare benefits. Any re- fund you receive because of the EIC can’t be counted as income when determining whether you or anyone else is eligible for benefits or assistance, or how much you or anyone else can receive, under any federal program or un- der any state or local program financed in whole or in part with federal funds.
Publication 596 (2025), Earned Income Credit (IRS)
A wrong claim can cost you the credit for 2 or 10 years afterward
If the IRS makes a final determination that your EIC claim was due to reckless or intentional disregard of the EIC rules, you are prohibited from claiming the credit for 2 years. If the determination is that your claim was due to fraud, you are prohibited from claiming the EIC for 10 years. During these disallowance periods, you cannot claim any EIC amount, whether it is the $664 credit for childless filers or the higher amounts such as $4,427 for one child, $7,316 for two children, or $8,231 for three or more children. Before the disallowance period ends, you must file Form 8862 to claim the EIC again.
Exception 2. Don’t file Form 8862 or take the EIC for: • 2 years after there was a final determination that your EIC claim was due to reckless or intentional disregard of the EIC rules, or • 10 years after there was a final determination that your EIC claim was due to fraud.
Publication 596 (2025), Earned Income Credit (IRS)
How each figure was verified
Each number below was read from a stored copy of the document named beside it, and checked to occur word for word in the quoted sentence. The digest is of that stored text.
Rev. Proc. 2025-32 (IRS)
- Maximum credit, one child
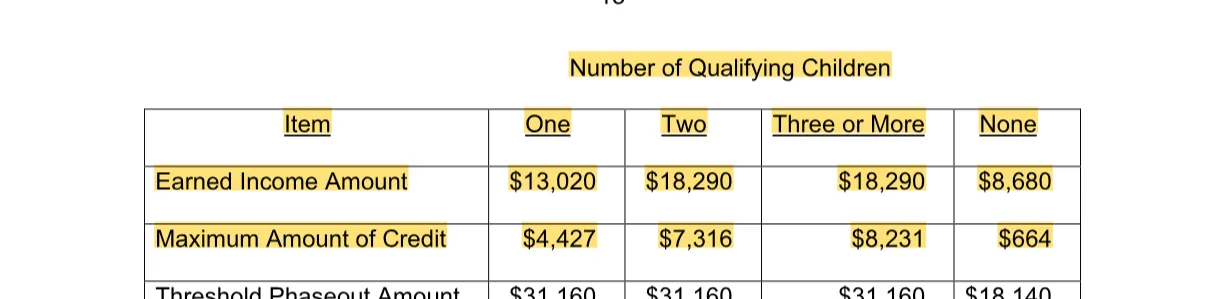
Number of Qualifying Children Item One Two Three or More None Earned Income Amount $13,020 $18,290 $18,290 $8,680 Maximum Amount of Credit $4,427 $7,316 $8,231 $664
- Maximum credit, two children
Number of Qualifying Children Item One Two Three or More None Earned Income Amount $13,020 $18,290 $18,290 $8,680 Maximum Amount of Credit $4,427 $7,316 $8,231 $664
- Maximum credit, three or more children
Number of Qualifying Children Item One Two Three or More None Earned Income Amount $13,020 $18,290 $18,290 $8,680 Maximum Amount of Credit $4,427 $7,316 $8,231 $664
- Maximum credit, childless filers
Number of Qualifying Children Item One Two Three or More None Earned Income Amount $13,020 $18,290 $18,290 $8,680 Maximum Amount of Credit $4,427 $7,316 $8,231 $664
- Earned income amount, one child
Earned Income Amount $13,020
- Earned income amount, two children
Earned Income Amount $13,020 $18,290
- Earned income amount, three or more children
Earned Income Amount $13,020 $18,290 $18,290
- Earned income amount, childless filers
Earned Income Amount $13,020 $18,290 $18,290 $8,680
- Phaseout begins (not filing jointly), one child
Number of Qualifying Children Item One Two Three or More None Earned Income Amount $13,020 $18,290 $18,290 $8,680 Maximum Amount of Credit $4,427 $7,316 $8,231 $664 Threshold Phaseout Amount (Married Filing Jointly) $31,160 $31,160 $31,160 $18,140 Completed Phaseout Amount (Married Filing Jointly) $58,863 $65,899 $70,244 $26,820 Threshold Phaseout Amount (All other filing statuses) $23,890 $23,890 $23,890 $10,860
- Phaseout begins (not filing jointly), two children
Number of Qualifying Children Item One Two Three or More None Earned Income Amount $13,020 $18,290 $18,290 $8,680 Maximum Amount of Credit $4,427 $7,316 $8,231 $664 Threshold Phaseout Amount (Married Filing Jointly) $31,160 $31,160 $31,160 $18,140 Completed Phaseout Amount (Married Filing Jointly) $58,863 $65,899 $70,244 $26,820 Threshold Phaseout Amount (All other filing statuses) $23,890 $23,890 $23,890 $10,860
- Phaseout begins (not filing jointly), three or more children
Number of Qualifying Children Item One Two Three or More None Earned Income Amount $13,020 $18,290 $18,290 $8,680 Maximum Amount of Credit $4,427 $7,316 $8,231 $664 Threshold Phaseout Amount (Married Filing Jointly) $31,160 $31,160 $31,160 $18,140 Completed Phaseout Amount (Married Filing Jointly) $58,863 $65,899 $70,244 $26,820 Threshold Phaseout Amount (All other filing statuses) $23,890 $23,890 $23,890 $10,860
- Phaseout begins (not filing jointly), childless filers
Number of Qualifying Children Item One Two Three or More None Earned Income Amount $13,020 $18,290 $18,290 $8,680 Maximum Amount of Credit $4,427 $7,316 $8,231 $664 Threshold Phaseout Amount (Married Filing Jointly) $31,160 $31,160 $31,160 $18,140 Completed Phaseout Amount (Married Filing Jointly) $58,863 $65,899 $70,244 $26,820 Threshold Phaseout Amount (All other filing statuses) $23,890 $23,890 $23,890 $10,860
- Phaseout begins (joint return), one child
Number of Qualifying Children Item One Two Three or More None Earned Income Amount $13,020 $18,290 $18,290 $8,680 Maximum Amount of Credit $4,427 $7,316 $8,231 $664 Threshold Phaseout Amount (Married Filing Jointly) $31,160 $31,160 $31,160 $18,140
- Phaseout begins (joint return), two children
Number of Qualifying Children Item One Two Three or More None Earned Income Amount $13,020 $18,290 $18,290 $8,680 Maximum Amount of Credit $4,427 $7,316 $8,231 $664 Threshold Phaseout Amount (Married Filing Jointly) $31,160 $31,160 $31,160 $18,140
- Phaseout begins (joint return), three or more children
Number of Qualifying Children Item One Two Three or More None Earned Income Amount $13,020 $18,290 $18,290 $8,680 Maximum Amount of Credit $4,427 $7,316 $8,231 $664 Threshold Phaseout Amount (Married Filing Jointly) $31,160 $31,160 $31,160 $18,140
- Phaseout begins (joint return), childless filers
Number of Qualifying Children Item One Two Three or More None Earned Income Amount $13,020 $18,290 $18,290 $8,680 Maximum Amount of Credit $4,427 $7,316 $8,231 $664 Threshold Phaseout Amount (Married Filing Jointly) $31,160 $31,160 $31,160 $18,140
- Credit reaches zero (not filing jointly), one child
Number of Qualifying Children Item One Two Three or More None Earned Income Amount $13,020 $18,290 $18,290 $8,680 Maximum Amount of Credit $4,427 $7,316 $8,231 $664 Threshold Phaseout Amount (Married Filing Jointly) $31,160 $31,160 $31,160 $18,140 Completed Phaseout Amount (Married Filing Jointly) $58,863 $65,899 $70,244 $26,820 Threshold Phaseout Amount (All other filing statuses) $23,890 $23,890 $23,890 $10,860 Completed Phaseout Amount (All other filing statuses) $51,593 $58,629 $62,974 $19,540
- Credit reaches zero (not filing jointly), two children
Number of Qualifying Children Item One Two Three or More None Earned Income Amount $13,020 $18,290 $18,290 $8,680 Maximum Amount of Credit $4,427 $7,316 $8,231 $664 Threshold Phaseout Amount (Married Filing Jointly) $31,160 $31,160 $31,160 $18,140 Completed Phaseout Amount (Married Filing Jointly) $58,863 $65,899 $70,244 $26,820 Threshold Phaseout Amount (All other filing statuses) $23,890 $23,890 $23,890 $10,860 Completed Phaseout Amount (All other filing statuses) $51,593 $58,629 $62,974 $19,540
- Credit reaches zero (not filing jointly), three or more children
Number of Qualifying Children Item One Two Three or More None Earned Income Amount $13,020 $18,290 $18,290 $8,680 Maximum Amount of Credit $4,427 $7,316 $8,231 $664 Threshold Phaseout Amount (Married Filing Jointly) $31,160 $31,160 $31,160 $18,140 Completed Phaseout Amount (Married Filing Jointly) $58,863 $65,899 $70,244 $26,820 Threshold Phaseout Amount (All other filing statuses) $23,890 $23,890 $23,890 $10,860 Completed Phaseout Amount (All other filing statuses) $51,593 $58,629 $62,974 $19,540
- Credit reaches zero (not filing jointly), childless filers
Number of Qualifying Children Item One Two Three or More None Earned Income Amount $13,020 $18,290 $18,290 $8,680 Maximum Amount of Credit $4,427 $7,316 $8,231 $664 Threshold Phaseout Amount (Married Filing Jointly) $31,160 $31,160 $31,160 $18,140 Completed Phaseout Amount (Married Filing Jointly) $58,863 $65,899 $70,244 $26,820 Threshold Phaseout Amount (All other filing statuses) $23,890 $23,890 $23,890 $10,860 Completed Phaseout Amount (All other filing statuses) $51,593 $58,629 $62,974 $19,540
- Credit reaches zero (joint return), one child
Number of Qualifying Children Item One Two Three or More None Earned Income Amount $13,020 $18,290 $18,290 $8,680 Maximum Amount of Credit $4,427 $7,316 $8,231 $664 Threshold Phaseout Amount (Married Filing Jointly) $31,160 $31,160 $31,160 $18,140 Completed Phaseout Amount (Married Filing Jointly) $58,863 $65,899 $70,244 $26,820
- Credit reaches zero (joint return), two children
Number of Qualifying Children Item One Two Three or More None Earned Income Amount $13,020 $18,290 $18,290 $8,680 Maximum Amount of Credit $4,427 $7,316 $8,231 $664 Threshold Phaseout Amount (Married Filing Jointly) $31,160 $31,160 $31,160 $18,140 Completed Phaseout Amount (Married Filing Jointly) $58,863 $65,899 $70,244 $26,820
- Credit reaches zero (joint return), three or more children
Number of Qualifying Children Item One Two Three or More None Earned Income Amount $13,020 $18,290 $18,290 $8,680 Maximum Amount of Credit $4,427 $7,316 $8,231 $664 Threshold Phaseout Amount (Married Filing Jointly) $31,160 $31,160 $31,160 $18,140 Completed Phaseout Amount (Married Filing Jointly) $58,863 $65,899 $70,244 $26,820
- Credit reaches zero (joint return), childless filers
Number of Qualifying Children Item One Two Three or More None Earned Income Amount $13,020 $18,290 $18,290 $8,680 Maximum Amount of Credit $4,427 $7,316 $8,231 $664 Threshold Phaseout Amount (Married Filing Jointly) $31,160 $31,160 $31,160 $18,140 Completed Phaseout Amount (Married Filing Jointly) $58,863 $65,899 $70,244 $26,820