2026 403(b) Contribution Limit
For 2026, the 403(b) Contribution Limit figures are $24,500 (Elective deferral limit), +$8,000 (Catch-up limit, age 50 and over) and +$11,250 (Catch-up limit, ages 60 through 63).
Effective 2026-01-01Source: Notice 2025-67 (IRS)Verified 2026-09-03
Compared with 2025
| Item | 2025 | 2026 | Change |
|---|---|---|---|
| Elective deferral limit | $23,500 | $24,500 | +$1,000 (+4.3%) |
| Catch-up limit, age 50 and over | +$7,500 | +$8,000 | +$500 (+6.7%) |
| Catch-up limit, ages 60 through 63 | +$11,250 | +$11,250 | +$0 (+0.0%) |
Who it applies to
Employees who make elective deferrals under a plan described in section 403(b), and the employers and plan administrators applying the limitation for the 2026 plan year. The notice writes the limitation by Code section rather than by plan type, stating it under section 402(g) for the elective deferrals described in that section. The $8,000 catch-up figure applies to participants aged 50 or over.
What changed this year, and why
Notice 2025-67 increases the limitation under section 402(g) on the exclusion for elective deferrals from $23,500 to $24,500 for 2026. That is the limitation that governs elective deferrals under a plan described in section 403(b). The catch-up contribution limitation under section 414(v) for individuals aged 50 or over increases from $7,500 to $8,000 for the same year.
Common questions
- What is the elective deferral limit for a section 403(b) plan in 2026?
- It is $24,500. Notice 2025-67 states that figure as the limitation under section 402(g) on the exclusion for elective deferrals, increased from $23,500. It caps what an employee elects to defer out of pay for the year. The notice states this as one limitation covering the elective deferrals described in section 402(g), rather than writing a separate figure for each kind of plan.
- What changed from the 2025 limits?
- Both figures moved. Notice 2025-67 states the section 402(g) elective deferral limitation as increased from $23,500 to $24,500, and the section 414(v) catch-up limitation for individuals aged 50 or over as increased from $7,500 to $8,000. The notice writes each change as a movement between two stated amounts, naming the old figure and the new one.
- How much extra can I contribute in 2026 if I am aged 50 or over?
- Notice 2025-67 states the catch-up contribution limitation under section 414(v) for an applicable employer plan, which generally applies to individuals aged 50 or over, as increased from $7,500 to $8,000 for 2026. The notice publishes it in its own sentence as an amount separate from the $24,500 elective deferral limitation, and it applies to plans other than the SIMPLE arrangements addressed separately.
- Why does the notice not name section 403(b) when it states this limit?
- Because Notice 2025-67 organises its amounts by Code section. The elective deferral figure is published as the limitation under section 402(g) on the exclusion for the elective deferrals described in that section, and $24,500 is the amount given for 2026. The only place the notice names section 403(b) directly is where it states the limitation for a safe harbor deferral-only plan, which is a different provision.
- If I contribute to two employer plans, do I get the limit twice?
- Notice 2025-67 states the section 402(g) limitation once, as a single figure on the exclusion for elective deferrals rather than a per-plan allowance. It states the limitation on deferrals under section 457 separately, and for 2026 that separate limitation carries the same $24,500 amount, raised from $23,500. The notice publishes no combined figure across plan types.
- Does the limit cover contributions my employer makes?
- No. The $24,500 figure is the limitation under section 402(g) on the exclusion for elective deferrals, which is what the employee elects to defer. Notice 2025-67 increases the overall limitation for defined contribution plans under section 415(c) in a separate sentence with its own amount. The two limitations are published as distinct items in the same notice.
- Is there a higher catch-up amount for ages 60 through 63 in 2026?
- Notice 2025-67 states a separate and higher catch-up limitation under section 414(v) for individuals who attain ages 60 through 63 during 2026. That amount is verified on the catch-up contribution page for this year rather than here, because the figures verified for this page are the section 402(g) elective deferral limitation and the section 414(v) catch-up limitation for individuals aged 50 or over.
- Where does the 2026 limit come from?
- Notice 2025-67, the annual IRS notice of amounts relating to retirement plans and IRAs as adjusted for changes in cost-of-living. Section 415 of the Internal Revenue Code provides for limitations on benefits and contributions under qualified retirement plans, and section 415(d) requires the Secretary of the Treasury to adjust them annually for cost-of-living increases. These figures are adjusted at the same time and in the same manner as the limitation of section 415(b), after rounding rules are applied.
Every amount on this page is a published figure rather than yours. The 403(b) contribution planner takes the number you enter and works it out against them, showing which published figure it used.
The other ceiling: total contributions of 100% of pay
The limit on annual additions is the first component used to determine your maximum amount contributable for the year. It caps the total dollars that can flow into the account from all sources combined: elective deferrals, nonelective employer contributions, and after-tax employee contributions. For 2026, the cap is the smaller of $72,000 or 100% of your includible compensation for your most recent year of service. In plain terms, the plan cannot accept more than you earned, and it cannot accept more than the statutory dollar ceiling no matter how high your pay is. If you participate in more than one account maintained by the same employer, you must aggregate the contributions across all those accounts when testing this limit. This cap operates independently of the elective-deferral limit; whichever figure is smaller governs what can be contributed in total before catch-up amounts are added.
The first component of your MAC is the limit on annual ad- ditions. This is a limit on the total contributions (elective deferrals, nonelective contributions, and after-tax contribu- tions) that can be made to your 403(b) account. The limit on annual additions is generally the lesser of: • $70,000 for 2025 and $72,000 for 2026, or • 100% of your includible compensation for your most recent year of service.
Publication 571 (2025), Tax-Sheltered Annuity Plans (403(b) Plans) (IRS)
Two limits, and your MAC is the lesser of them
Your maximum amount contributable for the year is found by comparing two separate ceilings. The first is the limit on annual additions, which caps all contributions from every source - salary reductions, employer nonelective amounts, and after-tax employee contributions - taken together. The second is the limit on elective deferrals, which for 2026 is $24,500 and applies only to salary-reduction contributions. Depending on what types of contributions are made to the account in a given year, only one or both of these limits may come into play. The overall maximum that can go in is the lesser of the two results. In practice, rank-and-file participants usually find the elective-deferral limit is the binding constraint, while highly compensated employees who receive large employer contributions may instead find that the annual-additions cap governs. Catch-up amounts for participants who are age 50 or older may be added on top of this figure without reducing it.
Components of Your MAC Generally, before you can determine your MAC, you must first figure the components of your MAC. The components of your MAC are: • The limit on annual additions (chapter 3), and • The limit on elective deferrals (chapter 4). How Do I Figure My MAC? Generally, contributions to your 403(b) account are limited to the lesser of: • The limit on annual additions, or • The limit on elective deferrals.
Publication 571 (2025), Tax-Sheltered Annuity Plans (403(b) Plans) (IRS)
The 15 years of service catch-up almost nobody uses
Long-service employees of qualifying organizations may access a special catch-up that sits on top of the regular elective-deferral limit. To qualify, you must have at least 15 years of service with an educational organization, hospital, home health agency, health and welfare agency, church, or associated organization, and the plan must permit it. When these conditions are met, the deferral ceiling is increased by a formula based on years of service and prior catch-up usage. For 2026, this special catch-up can raise total elective deferrals as high as $27,500. The provision is sometimes called the special catch-up or the years-of-service catch-up. If you also qualify for the age 50 catch-up in the same year, the plan must apply the 15-year service rule first and then apply the age 50 catch-up to any remaining room. Despite its availability, few participants use this benefit because the calculations are complex and the lifetime cap on prior catch-ups is often reached before participants become aware the provision exists.
If you qualify for the 15-year rule (sometimes referred to as the “special section 403(b) catch-up” or the “years-of-service catch-up”), your elective deferrals under this limit can be as high as $26,500 for 2025 and $27,500 for 2026.
Publication 571 (2025), Tax-Sheltered Annuity Plans (403(b) Plans) (IRS)
The age 50 catch-up sits on top of the limit
Participants who will reach age 50 by the end of the calendar year may make additional catch-up elective deferrals on top of the regular $24,500 limit, provided the plan permits them and the participant has already maxed out the basic elective-deferral amount for the plan year. For 2026, the age 50 catch-up allows an extra $8,000 in salary-reduction contributions. These catch-up dollars cannot come from after-tax employee contributions; they must be pre-tax or designated Roth deferrals. Importantly, catch-up amounts are not counted against the participant's maximum amount contributable, meaning they sit above and beyond the regular annual ceiling. If a participant is eligible for both the long-service catch-up and the age 50 catch-up in the same year, the plan must apply the long-service rule first and then apply the age 50 catch-up to any remaining room. Starting in 2025, participants who reach ages 60 through 63 during the year may qualify for an even higher catch-up amount.
If you will be age 50 or older by the end of the year, you may also be able to make additional catch-up contribu- tions. These additional contributions can’t be made with after-tax employee contributions.
Publication 571 (2025), Tax-Sheltered Annuity Plans (403(b) Plans) (IRS)
What to do when too much went in
When the total deposited into the account in a plan year exceeds the maximum amount contributable, the overage is an excess contribution. Catch-up amounts are excluded from this test, so only regular deferrals, employer contributions, and after-tax employee dollars count. At year-end - or early in the following year - the participant should refigure the maximum based on actual compensation and actual contributions to determine whether an excess exists. If employment status or compensation changes during the year, the limit should be refigured mid-year using revised estimates to prevent an excess from arising in the first place. Excess contributions can trigger income tax, additional taxes, and penalties. The specific consequences depend on the type of excess: for example, excess elective deferrals are treated differently from excess annual additions, and certain excess amounts may be corrected by distribution. The plan administrator or the participant's tax advisor should be consulted to determine the proper correction method for the particular type of excess.
Excess Contributions If your actual contributions (not including catch-up contri- butions) are greater than your MAC, you have an excess contribution. Excess contributions can result in income tax, additional taxes, and penalties.
Publication 571 (2025), Tax-Sheltered Annuity Plans (403(b) Plans) (IRS)
You have until April 15 to correct an excess deferral
When you contribute more than the annual limit to your 403(b) plan through salary deferrals, the IRS allows a specific window to fix the mistake and avoid double taxation. You must notify your plan administrator that an excess deferral occurred for the prior year. The plan then distributes the excess amount, together with any earnings that accrued on it while it sat in the account. Both the designation and the distribution must be completed by April 15 of the year after the year the excess deferral was made. If April 15 falls on a weekend or legal holiday, the deadline moves to the next business day. The excess deferral is included in your income for the year it was originally contributed, and the earnings are taxed in the year they are paid out to you. Missing the April 15 deadline means the excess stays in the plan and you lose the ability to receive a corrective distribution under this rule.
Correction of excess deferrals after the year. If you have excess deferrals for a year, you may receive a cor- recting distribution of the excess deferral no later than April 15 of the following year. The plan can distribute the excess deferral (and any income allocable to the excess) no later than April 15 of the year following the year the ex- cess deferral was made.
Publication 571 (2025), Tax-Sheltered Annuity Plans (403(b) Plans) (IRS)
There is no form to file - your employer reports it on your W-2
When you make pre-tax or designated Roth elective deferrals to your 403(b) plan, you do not report those amounts separately on your federal income tax return. Instead, your employer handles the reporting by entering the totals on your Form W-2. Pre-tax elective deferrals appear in box 12 of the W-2 with code E, while designated Roth elective deferrals appear in box 12 with code BB. In addition, box 13 of the W-2 has a Retirement plan checkbox that your employer marks to show you were covered by a workplace plan during the year. Because the deferrals are already reflected on the W-2 the employer sends to the IRS, there is no separate form for you to file to report the deferrals themselves. You still use the W-2 figures when preparing your return, but the deferral amounts are not added back into your wages or deducted again.
Generally, you don’t report elective deferrals to your 403(b) account (except Roth contributions) on your tax re- turn. Your employer will report elective deferrals on your 2025 Form W-2. Elective deferrals will be shown in box 12 with code E for pre-tax amounts and code BB for Roth amounts, and the Retirement plan box will be checked in box 13.
Publication 571 (2025), Tax-Sheltered Annuity Plans (403(b) Plans) (IRS)
The 15-year catch-up has a lifetime cap that shrinks as you use it
For 2026, the IRS lets eligible 403(b) participants use a 15-year rule that adds an extra amount on top of the regular elective deferral limit. To qualify, you must have at least 15 years of service with a qualifying educational organization, hospital, home health service agency, health and welfare service agency, church, or convention or association of churches (or an associated organization), and the plan document must allow it. The additional amount you can defer is the least of three figures, and the one that matters for the lifetime cap is $15,000. That $15,000 figure is reduced by the sum of any additional pre-tax elective deferrals you made in prior years because of this rule, plus any designated Roth contributions permitted in prior years because of this rule. Each year you use the catch-up, the remaining lifetime room shrinks by whatever was added, so the $15,000 represents the total lifetime benefit. Once prior use brings the remaining amount to zero, this part of the calculation provides no additional deferral space, even if you still meet the service requirement.
If you have at least 15 years of service with an educational organization (such as a public or private school), hospital, home health service agency, health and welfare service agency, church, or convention or association of churches (or associated organization) and it is allowed by the terms of the plan document, the limit on elective deferrals to your 403(b) account is increased by the least of: 1. $3,000; 2. $15,000, reduced by the sum of: a. The additional pre-tax elective deferrals made in prior years because of this rule, plus b. The aggregate amount of designated Roth contri- butions permitted for prior years because of this rule; or 3. $5,000 times the number of your years of service for the organization, minus the total elective deferrals made by your employer on your behalf for earlier years.
Publication 571 (2025), Tax-Sheltered Annuity Plans (403(b) Plans) (IRS)
Your limit is shared with every other elective-deferral plan you have
The annual elective deferral limit applies across every employer-sponsored plan that accepts salary deferrals, not just to a single 403(b) account. If you make elective deferrals to more than one 403(b) plan, or to a 403(b) plan and also to a 401(k) plan, a SIMPLE plan, a SAR-SEP, a section 501(c)(18) plan, or a Roth contribution program, all of those deferrals are added together to determine whether you have exceeded the limit. The combined total must not exceed the annual elective deferral limit for the year. This aggregation rule prevents someone who works for multiple employers, or who participates in more than one type of plan, from deferring more than the published cap by spreading contributions across several plans. It is your responsibility to track deferrals at every employer and plan and to coordinate them so the combined total stays within the limit.
403(b) plan and another retirement plan. If, during the year, contributions in the form of elective deferrals are made to other retirement plans on your behalf, you must combine all of the elective deferrals to determine if they are more than your limit on elective deferrals.
Publication 571 (2025), Tax-Sheltered Annuity Plans (403(b) Plans) (IRS)
How each figure was verified
Each number below was read from a stored copy of the document named beside it, and checked to occur word for word in the quoted sentence. The digest is of that stored text.
Notice 2025-67 (IRS)
- Elective deferral limit
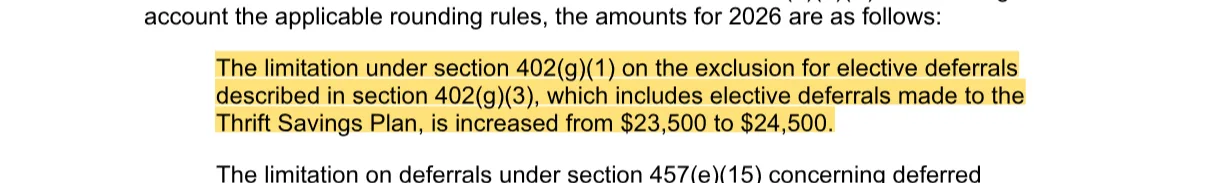
The limitation under section 402(g)(1) on the exclusion for elective deferrals described in section 402(g)(3), which includes elective deferrals made to the Thrift Savings Plan, is increased from $23,500 to $24,500.
- Catch-up limit, age 50 and over
The limitation under section 414(v)(2)(B)(i) for catch-up contributions to an applicable employer plan other than a plan described in section 401(k)(11) or section 408(p) that generally applies for individuals aged 50 or over is increased from $7,500 to $8,000.
- Catch-up limit, ages 60 through 63
The limitation under section 414(v)(2)(E)(i) for catch-up contributions to an applicable employer plan other than a plan described in section 401(k)(11) or section 408(p) that applies for individuals who attain age 60, 61, 62, or 63 in 2026 remains $11,250.